Written by: Luis Teran, Co-founder, CEO, TenantEvaluation
Key Takeaways
- Community association management in Florida runs on ten recurring disciplines across governance, finance, maintenance, people, community, and risk, and each one must be documented and executed the same way every time.
- Boards set policy while LCAMs execute operations; when those roles blur, both directors and management companies face higher liability.
- Financial discipline depends on a current operating budget, a reserve study updated at least every three years, monthly financial review, and a written collection policy with delinquency tracking.
- Resident onboarding, lease tracking, and fee collection work best inside a centralized, FCRA-compliant platform that delivers consistent screening, real-time visibility, and audit-ready records.
- TenantEvaluation replaces spreadsheets and scattered records with one auditable platform that documents decisions, tracks leases, and keeps every dollar traceable from application to payment.
1. Know And Follow The Governing Documents
The governing documents, including the declaration, bylaws, articles of incorporation, and rules and regulations, form the legal foundation for every enforcement, screening, and architectural decision the board makes. In Florida, three statutes frame the corporate structure and duties that sit beneath those documents: Chapter 718 (Condominium Act), Chapter 720 (Homeowners’ Association Act), and Chapter 617 (Florida Nonprofit Corporation Act, Substantially Revised By HB 797 Effective July 1, 2026).
Governing documents drive screening criteria, enforcement thresholds, and architectural review standards. A current, indexed set of governing documents supports consistent enforcement, defensible screening criteria in an FCRA or Fair Housing challenge, and reasoned architectural decisions that reduce personal exposure for directors and operational liability for the management company.
2. Separate The Board’s Role From The Manager’s Role
The board sets policy, approves the budget, and makes final approval decisions. The manager executes operations, collects documents, prepares recommendations, and implements the board’s decisions. When those roles overlap, the association loses structural clarity and risk increases for everyone involved.
In Florida, anyone compensated to manage an association with more than ten units or a budget above $100,000 must hold a Licensed Community Association Manager (LCAM) Credential Under Chapter 468, Part VIII. The LCAM license is distinct from a real estate license and requires pre-licensure education, a state exam, and 15 hours of continuing education per renewal cycle.
The operational answer to “How To Be A Good HOA Manager” is procedural and repeatable. Prepare each recommendation with a documented basis, present it to the board, execute the board’s decision, and keep managerial judgment separate from board authority. The manager who documents every recommendation and every execution step is the manager whose decisions stand up during a records request, a DBPR complaint, or litigation.
3. Financial Discipline: Operating Budget, Reserve Study, And Delinquency Management
Sound financial management rests on four connected practices: an annual operating budget, a current reserve study, monthly financial statements reviewed against budget, and a written delinquency collection policy.
CAI’s HOA budgeting best-practices guidance directs boards to adopt a written collection policy that specifies due dates, grace periods, late charges, notices, payment-plan options, and escalation steps, reviewed by qualified community association legal counsel. CAI frames assessment collection as a fiduciary duty, so boards protect the association’s financial stability while treating homeowners fairly and consistently.
CAI’s Reserve Study Standards recommend a full, site-visit reserve study at minimum every three years, with annual updates in the intervening years to reflect inflation, project completion, and changing conditions. CAI identifies percent funded, defined as reserve balance divided by the fully funded balance, as the clearest measure of reserve health. Reserve Study Standards note that percent funded alone does not determine adequacy, and associations below 30 percent funded carry a materially higher risk of special assessments.
Florida condominium budgets must fund reserves for capital expenditures and deferred maintenance. After HB 913 (2025), reserve waivers are no longer available for SIRS-mandated structural components in qualifying buildings, and a vote to waive those reserves becomes ineffective on the day it is adopted. Association Reserves’ analysis of more than 100,000 reserve studies it prepared found that 74% of its client associations fall below the 70%-funded level the industry considers healthy, though the firm notes this is its own client portfolio rather than a national census. That statistic underscores how much reserve discipline shapes an association’s financial stability.
Key financial KPIs to track include budget variance by line item, collection rate, and delinquency aging by account. A delinquency rate above 15% of units 60 or more days past due can make the community ineligible for conventional financing under Fannie Mae and Freddie Mac project eligibility rules.
4. Preventive Maintenance And Asset Inventory
A preventive maintenance program works best when it includes four elements: a dated calendar by component, a work-order log with completion dates, vendor certificates of insurance on file, and contract performance reviewed against scope.
The reserve study’s physical analysis functions as the asset inventory. A reserve specialist conducting a site visit assesses the condition and remaining lifespan of major common-area components including roofs, parking lots, swimming pools, fencing, exterior siding, elevators, clubhouse systems, and landscaping infrastructure. A maintenance calendar aligned with remaining useful life helps prevent minor common-area failures from becoming emergency repairs and keeps reserve projections close to actual conditions, which supports the board’s funding decisions with lenders and owners.
Cost data presented at CAI sessions showed construction and material costs jumped well beyond general inflation between 2020 and 2023, with roofing, concrete, and elevator work specifically cited. A maintenance calendar that relies on outdated cost assumptions produces reserve projections that understate future obligations. The Champlain Towers South collapse illustrated this risk, where the association held less than $800,000 in reserves against a fully funded target of $10.3 million.
5. Transparent Governance And Meetings
Transparent governance gives owners confidence that the board follows the rules the same way every time. That transparency rests on documented agendas, timestamped minutes, records access within statutory windows, quorum confirmation, conflict-of-interest disclosure, and ongoing board education.
Florida-specific requirements under Chapter 718 include:
- Board meetings open to unit owners with only two narrow exceptions: personnel matters and meetings with the association’s attorney concerning pending litigation
- Notice posted conspicuously on the property at least 48 continuous hours in advance with the agenda; email distribution alone does not satisfy the statute
- Fourteen-day mailed, delivered, or electronic notice where assessments or unit-use rules will be considered
- Under Florida Chapter 718, condominium owners can request official records in writing and the association must make them available within 5 working days; failure to produce them within 10 working days creates a rebuttable presumption of a statutory violation, exposing the association to statutory damages up to $500 and the prevailing owner’s attorney fees
- Director certification within 90 days of election or appointment, plus at least four hours of DBPR-approved education and one hour of annual continuing education
- Conflict-of-interest disclosure under § 617.0832 and § 718.3027, with the proposed conflict activity listed on the meeting agenda and all related documents attached
Common Red Flags Of HOA Mismanagement
Mismanagement usually reflects weak structure rather than one bad decision. Typical red flags include:
- No written collection policy, or a policy that is not applied consistently across all accounts
- No current reserve study, or a reserve study that has not been updated with a site visit in more than three years
- Minutes that record decisions without the basis for them, with no reference to reports reviewed, advisors consulted, or votes cast
- Enforcement that varies by owner rather than by the violation and the governing documents
- Records requests that stall past the statutory response window
- Vendor contracts awarded without documented comparison of bids or scope
Structural Signs Of A Dysfunctional HOA Board
Dysfunction also shows up in structure and process. Common signs and practical fixes include:
- Decisions Made Outside Noticed Meetings → Fix: adopt a 12-month meeting calendar and post every notice on the property as required
- No Conflict-Of-Interest Disclosure → Fix: require written disclosure on the agenda before any vote involving a director’s financial interest, per § 718.3027 and revised § 617.0832
- No Board Education → Fix: schedule director certification and annual continuing education at the start of each fiscal year
- An Authority Matrix That Exists Only In Theory → Fix: publish a written authority matrix separating board policy from manager execution and reference it in every board meeting
- A Manager Executing Policy The Board Never Adopted → Fix: require every operational procedure to trace to a board resolution or governing-document provision
6. Resident Onboarding As A Governance And Risk Practice
The same governance discipline that governs meetings also governs who gets to move in. Resident onboarding functions as a governance and risk practice, not just a paperwork task. Screening criteria must tie to the governing documents, apply consistently to every applicant, and run inside an FCRA-compliant workflow with permissible-purpose controls, adverse-action notices, and complete record retention. For screening detail specific to Florida community associations, see Best Practices For Florida Community Association Screening.
TenantEvaluation is built specifically for community associations and management companies, with FCRA compliance as the foundation. Operating across 5,000+ communities and processing approximately 100,000 applications per year, TenantEvaluation maintains direct credit bureau reseller relationships with TransUnion and Equifax, built-in adverse action workflows, and A–Z onboarding from application intake through final decision and record retention. The board-of-directors dashboard, a dedicated review and voting panel with real-time application tracking, is a capability competitors do not offer.
QuickApprove accelerates resident approvals for CAMs, boards, and property management teams inside one connected platform. It provides real-time application tracking, reduces manual follow-ups, and delivers a board-ready approval process with automated communication support, customized approval letters, and a personalized welcome package. The result is a faster, more consistent approval process that holds up during high-volume seasons without sacrificing control, compliance, or visibility.
For age-restricted communities, 55+ Communities Verification standardizes application handling and documentation for Florida condos and HOAs. Community Association Managers use it to reduce manual work and strengthen internal processes across age-restricted portfolios.
Identity Fraud And Synthetic Identities In Community Associations
Synthetic identities are built from a real but unmonitored Social Security number, often one issued to a child, an undocumented immigrant, or a recently deceased person, paired with fabricated biographic details, then aged over 12 to 18 months until the synthetic identity carries a credit score above 700. A credit pull confirms that a file exists, not that the applicant matches the person the number was issued to.
Standard credit screening cannot detect CPN-based synthetic identities because a bureau pull only confirms that a number exists and a score is attached. The shift from document-based review to biometric identity confirmation closes this gap.
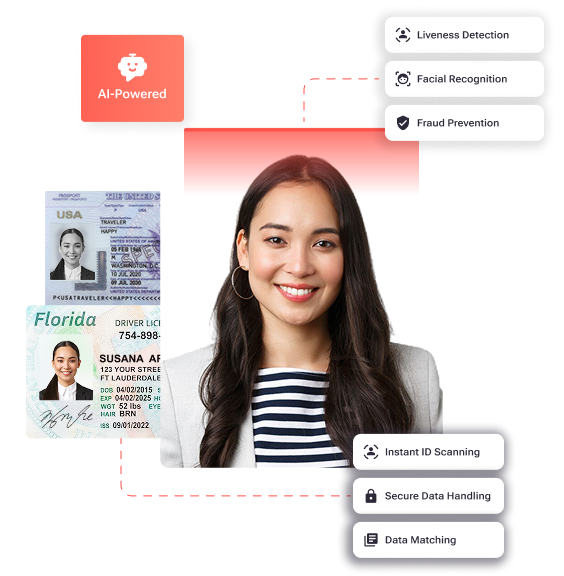
IDVerify validates the government ID, runs AI-powered liveness detection, and performs biometric selfie-to-ID comparison inside the TenantEvaluation screening workflow. Identity confirmation occurs before screening authorization, which strengthens permissible-purpose validation and supports FCRA-aligned workflows and audit defensibility.
7. Lease Tracking And Fee Collection As Operational Control
Centralized lease visibility and connected fee collection give boards and managers real operational control. For a full comparison of software options that support these workflows, see Community Association Management Software: A 2026 Guide.
TenantEvaluation’s Lease Tracking delivers centralized, real-time lease visibility and lifecycle control from application to occupancy. Built for CAMs, boards, property management companies, and community operations teams, it connects resident onboarding, unit data, approvals, and lease documentation in one platform. Real-time lease status, automated lease document collection during onboarding, and unit-level tracking replace spreadsheets and scattered email chains. Every lease record is searchable and audit-ready, which improves operational efficiency and compliance readiness.
TEpayments by Zinc is a connected payment workflow inside TenantEvaluation that collects application fees and deposits during resident onboarding. Payments go directly to the Association’s designated account, and TenantEvaluation never holds the funds. Each Association defines what is collected and at which stage, and the workflow adapts to the property’s process rather than forcing a universal sequence.
The table below contrasts how four core operating disciplines behave under a manual standard versus a connected one, so boards and managers can see where spreadsheets and email chains create the most exposure.
| Attribute | Manual Operating Standard | TenantEvaluation-Connected Standard |
|---|---|---|
| Governing-Document Enforcement | Screening criteria stored in email chains and institutional memory; enforcement consistency depends on individual staff recall | Screening criteria configured per community profile inside the platform; every application evaluated against the same documented criteria with a built-in audit trail |
| Onboarding And Identity Verification | Document uploads reviewed manually; no biometric confirmation; synthetic identity exposure unaddressed by credit pull alone | IDVerify+ runs government ID validation, AI-powered liveness detection, and biometric selfie-to-ID comparison natively inside the workflow before screening authorization |
| Lease Visibility | Lease copies stored across folders, inboxes, and spreadsheets; no centralized status; occupancy confirmation requires manual follow-up | Real-time lease status connected to onboarding, unit data, and approvals; automated lease document collection; searchable, audit-ready digital records |
| Fee And Deposit Collection | Payment confirmations chased by email and phone; fees tracked in disconnected spreadsheets; applicants unsure what, when, and where to pay | TEpayments by Zinc collects fees and deposits inside the onboarding workflow; payments go directly to the Association’s designated account; TenantEvaluation never holds the funds |
8. Measuring Management Performance
Management performance becomes clear when it is measured against the recurring operating cycle instead of one-off events. The KPIs that matter to a board and a management company operations lead include:
- Budget variance by line item, reviewed monthly against the adopted budget
- Collection rate, the share of assessments collected within the grace period, tracked against the written collection policy
- Work-order completion time, measured from submission to close and reviewed against the preventive maintenance calendar
- Violation-processing time, measured from identification to notice to hearing to resolution and reviewed for consistency across all owners
These KPIs matter only when the underlying data is documented and retrievable. An association that runs on spreadsheets and email chains struggles to produce consistent KPI data, which makes it harder to demonstrate to a board, a lender, or a regulator that the operating cycle works as intended.
9. Liability And Governance Questions
Personal Liability For Florida HOA Board Members
Florida Statute § 617.0830 imposes three core fiduciary duties on directors of Florida nonprofit corporations, including community associations: to act in good faith, with the care an ordinarily prudent person in a like position would exercise under similar circumstances, and in a manner the director reasonably believes to be in the best interests of the corporation. This statute anchors the business-judgment rule that Florida courts apply to HOA and condominium board decisions.
HB 797, effective July 1, 2026, substantially rewrote § 617.0830 and codified a Caremark-style oversight duty, meaning directors must actively monitor finances, vendors, insurance, and statutory compliance. Under revised § 617.0834, directors and officers are generally immune from personal liability for monetary damages unless their breach constitutes a violation of criminal law, an improper personal benefit, conscious disregard or willful misconduct, or recklessness, bad faith, or malicious purpose.
The business-judgment protection depends on directors actually informing themselves before voting. Documented decisions, audit trails, conflict-of-interest disclosure, and board education all help reduce exposure. This article does not constitute legal advice; boards should consult qualified community association legal counsel on their specific circumstances.
10. Career And Credential Context For Community Association Managers
Florida’s LCAM credential under Chapter 468, Part VIII sets the legal requirement to practice, and many managers build beyond that baseline. Voluntary national credentials such as the CMCA, AMS, and PCAM represent the professional standard for community association management certification beyond the state license, with the AMS and PCAM designations offered through the Community Associations Institute and the CMCA certification administered by the CAI-established Community Association Managers International Certification Board (CAMICB). For practitioners building a career in this field, community association management jobs increasingly require both the LCAM license and demonstrated experience with the financial, governance, and onboarding disciplines described in this article.
Frequently Asked Questions
What Are The Duties Of A Community Association Manager
A Florida Licensed Community Association Manager (LCAM), credentialed under Chapter 468, Part VIII, is responsible for executing the board’s decisions rather than making them. The LCAM’s operational duties include collecting and organizing documents, coordinating vendors, processing payments, maintaining records, preparing financial reports and board meeting packages, managing the onboarding and screening workflow, and tracking lease and occupancy status. The board sets policy, and the LCAM executes it while preparing recommendations that inform the board’s next decision. The LCAM who documents every recommendation and every execution step is the one whose decisions survive a records request or a regulatory complaint.
How To Be A Good HOA Manager
At the operational level, a good HOA manager prepares every recommendation with a documented basis, presents it to the board in a format that enables an informed vote, and then executes the board’s decision exactly as adopted. In practice, that approach requires a current set of governing documents, a written authority matrix, a preventive maintenance calendar, a delinquency aging report reviewed at every board meeting, and an onboarding and screening workflow that is FCRA-compliant by design. The manager who can produce a complete audit trail for any decision, from the recommendation through the board vote through the execution, is the manager who remains defensible when a decision is questioned.
Can HOA Board Members Be Held Personally Liable In Florida
Florida Statute § 617.0830, substantially revised by HB 797 effective July 1, 2026, supplies the general standard of care for board decision-making. Directors who rely in good faith on reports from officers, employees, professional advisors, or board committees are generally protected for that reliance, provided they inform themselves before voting. Under revised § 617.0834, directors and officers are generally immune from personal liability for monetary damages unless their breach constitutes a violation of criminal law, an improper personal benefit, conscious disregard or willful misconduct, or recklessness, bad faith, or malicious purpose. As noted in Section 9, the strength of that protection depends on informed decisions supported by documentation and appropriate oversight. This is not legal advice; consult qualified community association legal counsel for guidance specific to your association’s circumstances.
Closing Implementation Checklist
The recurring operating cycle for a Florida LCAM or board president includes the following steps:
- Confirm governing documents are current, indexed, and accessible to the board and manager
- Publish a written authority matrix separating board policy from manager execution
- Adopt the annual budget and confirm reserve funding against the current reserve study
- Set the preventive maintenance calendar and asset inventory, tied to the reserve study’s physical analysis
- Schedule board education, director certification, and conflict-of-interest disclosure procedures
- Configure screening criteria, FCRA permissible-purpose controls, and adverse-action workflows inside the onboarding platform
- Centralize lease records and confirm occupancy status for every unit
- Connect fee and deposit collection to the onboarding workflow so payments are traceable from submission to the Association’s designated account
- Review budget variance, collection rate, work-order completion, and violation-processing time at every board meeting
Community association management best practices function as a recurring operating cycle. Run the cycle on paper, and the association remains defensible only until the first records request or regulatory complaint. Run it inside one connected platform, and every decision is documented, every lease is visible, and every dollar is traceable. Use TenantEvaluation to compare your onboarding, lease-tracking, and payment workflows against the standard described in this article.
