Written by: Luis Teran, Co-founder, CEO, TenantEvaluation | Last updated: August 19, 2026
Key Takeaways for Florida CAMs and Boards
- FCRA compliance requires a documented, repeatable workflow that covers every step from written criteria through record retention to reduce statutory damages and FTC enforcement risk.
- Manual screening creates compounding liability through inconsistent criteria, missing disclosures, and fragmented records that regulators and plaintiffs can exploit.
- TenantEvaluation delivers FCRA-compliant consumer reports through bureau-direct TransUnion and Equifax data, removing gray-market sources and maintaining audit-ready chains of custody.
- The 12-step workflow uses tools such as IDVerify+ for biometric identity verification, automated adverse action notices, QuickApprove for board-ready approvals, and centralized Lease Tracking for full lifecycle visibility.
- TenantEvaluation replaces manual risk with an end-to-end, board-ready platform purpose-built for Florida community associations.
The Problem: Manual Screening Drives Compliance Risk and Delays
Florida CAMs and HOA boards that rely on manual screening workflows face growing, measurable risk. FCRA filings increased 37.4% in 2025 compared with 2024. On July 9, 2026, the FTC announced a $2.25 million settlement with tenant screening vendor RentGrow Inc. over duplicate eviction and criminal records, an undisclosed data source, and disputes closed without investigation.
Willful FCRA violations expose associations to statutory damages of $100–$1,000 per violation plus punitive damages and attorney fees. The adverse action notice violation is the most frequently cited FCRA infraction in residential landlord enforcement actions. Florida-specific rules add more complexity. Under the Florida Condominium Act (Chapter 718), a condominium association may charge a screening or transfer fee capped at $100 per applicant. Inconsistent criteria, missing disclosures, and fragmented lease records create the exact conditions regulators and plaintiffs target.
These risks require a structured operational response that addresses every step of the screening workflow. See how TenantEvaluation eliminates FCRA violation risk with bureau-direct data and automated adverse action notices by scheduling a compliance workflow demo.
The Solution: TenantEvaluation’s End-to-End FCRA Workflow for Florida Communities
TenantEvaluation is built for community associations and management companies, with FCRA compliance as the foundation, not an afterthought. The platform serves more than 5,000 communities and processes about 100,000 applications per year across Florida. As a direct reseller of TransUnion and Equifax data, TenantEvaluation accesses bureau data under strict bureau rules with no gray-market or offshore sources, which helps keep associations protected from liability exposure.
Core capabilities include QuickApprove for accelerated, board-ready approvals, IDVerify+ for biometric identity confirmation, 55+ Communities Verification for age-restricted documentation standardization, Lease Tracking for real-time lease lifecycle visibility, and TEpayments by Zinc for connected fee and deposit collection within the onboarding workflow. Payments move directly from the applicant to the association’s designated account and are never held by TenantEvaluation.
12-Step FCRA-Compliant Tenant Screening Workflow
- Establish Written Screening Criteria Before Advertising. The U.S. Department of Housing and Urban Development recommends recording tenant screening criteria using a worksheet or checklist with each screening element plus acceptable and unacceptable responses, or a spreadsheet with categories and evaluation formulas. Criteria must be objective, measurable, and applied identically to every applicant. Include minimum income thresholds, credit score floors, rental history standards, and criminal history parameters. Florida associations should document criteria in governing documents or a board resolution before accepting the first application.
- Obtain a Standalone Written Disclosure and Authorization. Landlords must obtain clear written authorization before ordering a tenant screening report, and the authorization must be separate and explicit, because verbal permission does not meet the statute. The disclosure document must stand alone and cannot be buried in the lease or application. TenantEvaluation delivers this as a discrete, timestamped step inside the digital application workflow.
- Confirm Permissible Purpose. Housing decisions qualify as a permissible purpose for obtaining consumer reports under 15 U.S.C. § 1681a(d). The rental application creates permissible purpose when screening is for housing eligibility. Associations must not reuse old reports for new applications. IDVerify+ strengthens permissible-purpose validation by confirming identity before screening authorization proceeds.
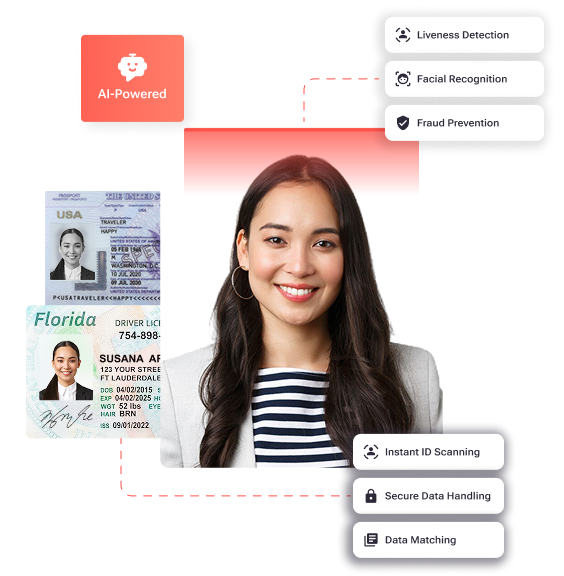
- Verify Applicant Identity with Biometric Confirmation. A 2021 CFPB advisory opinion stated that consumer reporting agencies using name-only matching procedures are not using reasonable procedures to assure maximum possible accuracy under FCRA section 607(b). IDVerify+ moves communities from document-based review to biometric-backed identity confirmation using government ID validation, AI-powered liveness detection, and biometric selfie-to-ID comparison. All steps occur natively inside TenantEvaluation, with no external portals.
- Order Reports Through an FCRA-Certified Consumer Reporting Agency. Any third-party tenant screening service that compiles information about applicants and reports it to landlords qualifies as a consumer reporting agency subject to FCRA requirements. TenantEvaluation acts as a direct reseller of TransUnion and Equifax data, accessed under strict bureau rules with regular compliance reviews and audits.
- Review Reports Against Written Criteria Consistently. Common FCRA compliance failures include applying criteria inconsistently and using criminal history without checking state and local restrictions. HUD guidance from 2016 warns that blanket criminal history exclusions in tenant screening can constitute unlawful disparate impact under the Fair Housing Act. Reviewers must evaluate reports against the same documented standards for every applicant to support defensible decisions.
- Issue a Pre-Adverse Action Notice Before Final Denial. The FCRA two-step adverse-action process requires a pre-adverse action notice plus a copy of the consumer report and the FTC Summary of Rights before a final denial notice is issued, and skipping the pre-adverse action step constitutes a willful violation. TenantEvaluation’s automated adverse action workflow generates this notice with the required attachments at the correct workflow stage.
- Issue the Final Adverse Action Notice with All Required Elements. The FCRA-mandated adverse action notice must include the name, address, and telephone number of the CRA that supplied the report, including a toll-free number if the CRA maintains nationwide files, a statement that the CRA did not make the decision and cannot provide specific reasons for it, and notice of the right to a free copy of the report within 60 days and the right to dispute inaccuracies. An adverse action notice is required even when information from the consumer report played only a minor role in the decision.
- Support the Applicant’s Dispute Rights. Tenant-screening agencies must investigate disputes of inaccurate or unverifiable information within 30 days under FCRA Section 1681i. Associations must not re-screen or re-deny during an active dispute period without a new, compliant authorization. TenantEvaluation maintains a clear separation between decision-making by the association and data provision by TenantEvaluation, which preserves audit defensibility.
- Retain and Dispose of Records According to FCRA and Florida Requirements. FCRA reporting limits include late payments, charge-offs, collections, and eviction records for 7 years, and Chapter 7 bankruptcy for 10 years. Florida’s Condominium Act (Chapter 718) requires condominium associations to make official records available for inspection within 5 working days after a written request. These rules create a dual burden: records must meet federal retention expectations and remain retrieval-ready for Florida inspection deadlines. TenantEvaluation’s platform addresses both needs by auto-redacting sensitive PII and maintaining searchable, audit-ready digital records from application through occupancy.
- Route Approvals Through the Board Voting Dashboard. Florida condominium and HOA boards retain final approval authority under their governing documents. QuickApprove gives board members a dedicated review and voting panel with AI-generated applicant summaries, real-time application tracking, automated communication support, customized approval letters, and a personalized welcome package. This replaces email chains and spreadsheets with a connected, board-ready approval process inside TenantEvaluation while preserving control, compliance, and visibility.
- Connect Approval to Lease Tracking and Fee Collection. Once the board approves, the workflow must connect to lease documentation and payment collection without breaking the audit trail. TenantEvaluation’s Lease Tracking connects resident onboarding, unit data, approvals, and lease documentation into one centralized, real-time workflow. Boards gain clear visibility into lease status, including active, pending, expired, or missing leases, along with audit-ready digital records. TEpayments by Zinc collects application fees, deposits, and other required resident payments within the same onboarding process, with payments going directly from the applicant to the association’s designated account.
Compliance Checklist and Templates for Florida Associations
This checklist serves as your audit-ready compliance verification tool for the 12-step workflow. Use it before moving any application to board review to confirm that every required document exists and is properly timestamped for the current application cycle.
- Written screening criteria worksheet covering income, credit, rental history, and criminal history parameters, completed before advertising
- Standalone FCRA disclosure document, separate from lease and application
- Signed written authorization from each applicant, timestamped and stored
- Biometric identity verification result from IDVerify+, including ID authenticity, liveness status, biometric match result, and redacted ID copy
- Consumer report ordered through an FCRA-certified CRA using bureau-direct data only
- Criteria evaluation worksheet using the same form for every applicant
- Pre-adverse action notice with consumer report copy and FTC Summary of Rights, issued before final denial
- Final adverse action notice with CRA name, address, toll-free number, CRA non-decision statement, 60-day free copy right, and dispute rights
- Dispute log capturing dates, outcomes, and any re-screening authorization
- Record retention schedule documenting a 7-year minimum for eviction and adverse credit data and Florida official records compliance
- Board voting record from the QuickApprove dashboard, including timestamped votes and approval letters
- Lease document stored in Lease Tracking with status confirmed as active and connected to the unit-level onboarding record
For age-restricted communities, 55+ Communities Verification standardizes how age-restricted requirements are handled across applications, which reduces manual work, improves documentation consistency, and strengthens operational efficiency and control for Florida condos and HOAs.
Frequently Asked Questions
Permissible Purpose for Florida Associations Under the FCRA
Permissible purpose is the legal basis that authorizes a community association to obtain a consumer report on an applicant. For housing decisions, the rental or purchase application creates permissible purpose because the association is screening for housing eligibility, which the FCRA recognizes. To establish and document permissible purpose, the association must collect a signed, standalone written authorization from the applicant before ordering any consumer report. This authorization must be a separate document, not embedded in the lease or general application. TenantEvaluation builds this step directly into the digital application workflow and generates a timestamped authorization record for every applicant. IDVerify+ further strengthens permissible-purpose defensibility by confirming the applicant’s identity before screening authorization proceeds, which ensures the report is ordered on a verified individual.
Why Self-Screened Reports Do Not Protect Florida HOAs and Condos
Self-screening, where an applicant orders their own report and submits it to the association, does not satisfy FCRA requirements for the association’s screening workflow. The FCRA governs reports obtained by the association from a consumer reporting agency for a permissible purpose. When an applicant submits their own report, the association has no verified chain of custody, no confirmation that the report is current or unaltered, and no direct relationship with the CRA that produced it. These gaps create accuracy and audit-trail problems that expose the association to liability. TenantEvaluation resolves this by ordering reports directly through its bureau-direct relationships with TransUnion and Equifax and maintaining a complete, auditable record from authorization through report delivery and decision.
Record Retention Timelines for Florida Tenant Screening Files
Record retention requirements for Florida community associations come from federal FCRA rules and Florida’s Condominium Act (Chapter 718) or HOA statute (Chapter 720). Under the FCRA, adverse credit information, eviction records, and related consumer report data are subject to 7-year reporting limits, and associations should retain screening records for at least that period to defend against disputes or enforcement inquiries. Under Florida’s Condominium Act, associations must make official records available for inspection within 5 working days of a written request, and failure to comply with a Florida condominium records request can result in statutory damages of $50 per day, up to a maximum of $500, for willful noncompliance after the deadline. TenantEvaluation’s Lease Tracking and document management capabilities maintain searchable, audit-ready digital records from application submission through occupancy, with auto-redaction of sensitive PII to reduce data breach exposure during the retention period.
Required Language for FCRA-Compliant Adverse Action Notices
A compliant adverse action notice for tenant screening must include the name, address, and toll-free telephone number of the consumer reporting agency that supplied the report, a statement that the CRA did not make the decision to take the adverse action and cannot provide the specific reasons for it, notice of the applicant’s right to obtain a free copy of the consumer report from the CRA within 60 days of receiving the notice, and notice of the applicant’s right to dispute the accuracy or completeness of any information in the report. The notice is required even if the consumer report was only one of several factors in the denial. Florida associations must also issue a pre-adverse action notice, including a copy of the report and the FTC Summary of Rights, before the final adverse action notice is sent. TenantEvaluation’s automated adverse action workflow generates both notices with all required elements at the correct stage of the workflow.
Handling Age-Restricted 55+ Screening Requirements in Florida
Florida condos and HOAs operating as age-restricted communities under the Housing for Older Persons Act face documentation and consistency requirements that generic screening platforms rarely handle well. TenantEvaluation’s 55+ Communities Verification is a built-in capability that standardizes how age-restricted requirements are handled across applications, which reduces manual work, improves documentation consistency, and strengthens operational efficiency and control. It replaces fragmented manual processes that rely heavily on emails, PDFs, and follow-ups with a more structured and consistent workflow designed for Community Association Managers and boards. This capability supports documentation and consistency for internal operational control and does not replace legal guidance from qualified counsel on HOPA compliance.
Conclusion: Put a Defensible Workflow in Place Tomorrow
Florida CAMs and HOA boards that continue using manual screening workflows carry growing liability. The 12-step workflow above provides a clear sequence, from written criteria through lease tracking, that replaces spreadsheets, email chains, and missing adverse action notices with a defensible, board-ready process. The TenantEvaluation platform integrates the identity, approval, and tracking capabilities detailed above into a single audit-ready workflow built for community associations.
