Written by: Luis Teran, Co-founder, CEO, TenantEvaluation | Last updated: September 10, 2026
Key Takeaways For Florida Condo Boards
- Identity fraud in condo applications is surging, with a 500% rise in AI-generated fraudulent documents and 93.3% of operators reporting fraud in the past year.
- A red flag signals the need for verification before any decision is made. Every anomaly requires an independent check.
- Behavioral red flags such as pressure to bypass verification, refusal of reasonable checks, and undocumented third-party payment arrangements are strong indicators for closer review.
- Document-based screening alone no longer protects communities. Biometric identity verification and source-confirmed income checks now play a central role against modern AI-generated fraud.
- See how TenantEvaluation builds FCRA-compliant verification workflows for Florida associations.
The Flag-To-Verification Map For Condo Tenant Screening
This section pairs each major red flag with the verification step that resolves it. Each step builds a defensible record of due diligence before the board makes a decision.
- Document Inconsistencies Across Pages. Start by comparing name, date of birth, address history, and employer across every uploaded document. When those details do not match, the mismatch signals that the file needs a second look. A pay stub employer that differs from the background-check employer may reflect a recent job change or a fabrication, and only an independent verification step can tell you which. That is why mismatches go to manual review rather than automatic rejection.
- Unverifiable Income. Contact the employer through an independently sourced number found on a public directory or the company website. Employer verification letters are among the easiest documents to fabricate because a logo can be lifted from a company website and a fake HR contact number routed to a co-conspirator. Request consecutive pay stubs and confirm that net pay appears as a matching direct deposit on the same schedule.
- Identity Details That Do Not Reconcile. Confirm the ID against issuing-state records using a document-verification service, then tie the live applicant to the ID photo through biometric verification. Modern counterfeit driver's licenses reproduce holograms, microprint, and UV-reactive features, which defeats manual visual inspection. MRI Real Estate Software purchased 200 AI-generated fake IDs and found that optical card readers flagged only 26% of them.
- Rushed Timelines And Pressure To Skip Steps. Hold the standard sequence and resist shortcuts. Document the pressure and the association's response in the applicant file. Unusual pressure for immediate approval is a documented warning sign of rental application fraud.
- Third-Party Payment Arrangements. Confirm the source of funds and who is obligated on the lease. An unrelated party paying rent with no documented relationship to the applicant requires verification of the relationship and the source of funds, and the association should record that documentation in the file.
- Thin Or Inconsistent Credit File. Treat a thin file as a trigger for deeper checks. Synthetic identities are built specifically to produce clean credit pulls by combining a real but unmonitored Social Security number with a fabricated name and date of birth, then aging a clean credit file over twelve to eighteen months. Cross-check address history and identity consistency across all submitted documents.
Every anomaly should lead to a documented verification step and a clear note in the file that explains what was checked and what was found.
Map every red flag to a documented verification step inside one workflow.
Behavioral Red Flags During The Condo Application Process
Behavioral signals differ from document anomalies. They show how an applicant responds to the verification process itself and often reveal which files deserve closer review.
- Pressure To Bypass Process. Legitimate applicants ask how long verification takes. Fraud-focused applicants push staff to skip steps or rush decisions. The weakest link in multifamily fraud defense is the workflow rather than the tool, because rushed reviews and handoffs are where fraud enters. A legitimate applicant who is in a hurry still complies with verification when the process is explained clearly.
- Refusal Of Reasonable Verification. Declining biometric identity confirmation or employer contact is a behavioral signal that deserves attention. Applicants who refuse to authorize screening reports are a documented red flag. A legitimate applicant may be confused or unfamiliar with the process, and staff can resolve that with a clear explanation. Continued refusal after explanation is a different matter entirely.
- Third-Party Payment With No Documented Relationship. Rent paid by an unrelated party, especially one who cannot be identified or contacted, suggests that the applicant may not be the intended occupant. A legitimate co-signer arrangement involves a documented, verifiable relationship and a party who is obligated on the lease.
Income And Employment Verification That Holds Up
Professional-looking documents do not prove anything by themselves. AI tools can create a coherent identity package, including photo ID, employment letter, bank statement, and rental reference, with enough internal consistency to convince a reviewer they are real. Verification must rely on source confirmation instead of document appearance.
Independent employer contact means calling a number found through a public directory or the company's official website. The false-employer attack is the highest-velocity fraud pattern in 2024–2026: the applicant lists a friend or shell LLC as their employer, provides a phone number that goes to a coordinating accomplice, and submits matching fabricated pay stubs, which defeats a standard employer call. Requesting two or three consecutive pay stubs forces year-to-date totals, deduction structures, and deposit patterns to align across every document at once. Forgers who can produce a convincing single stub often fail that test across a sequence.
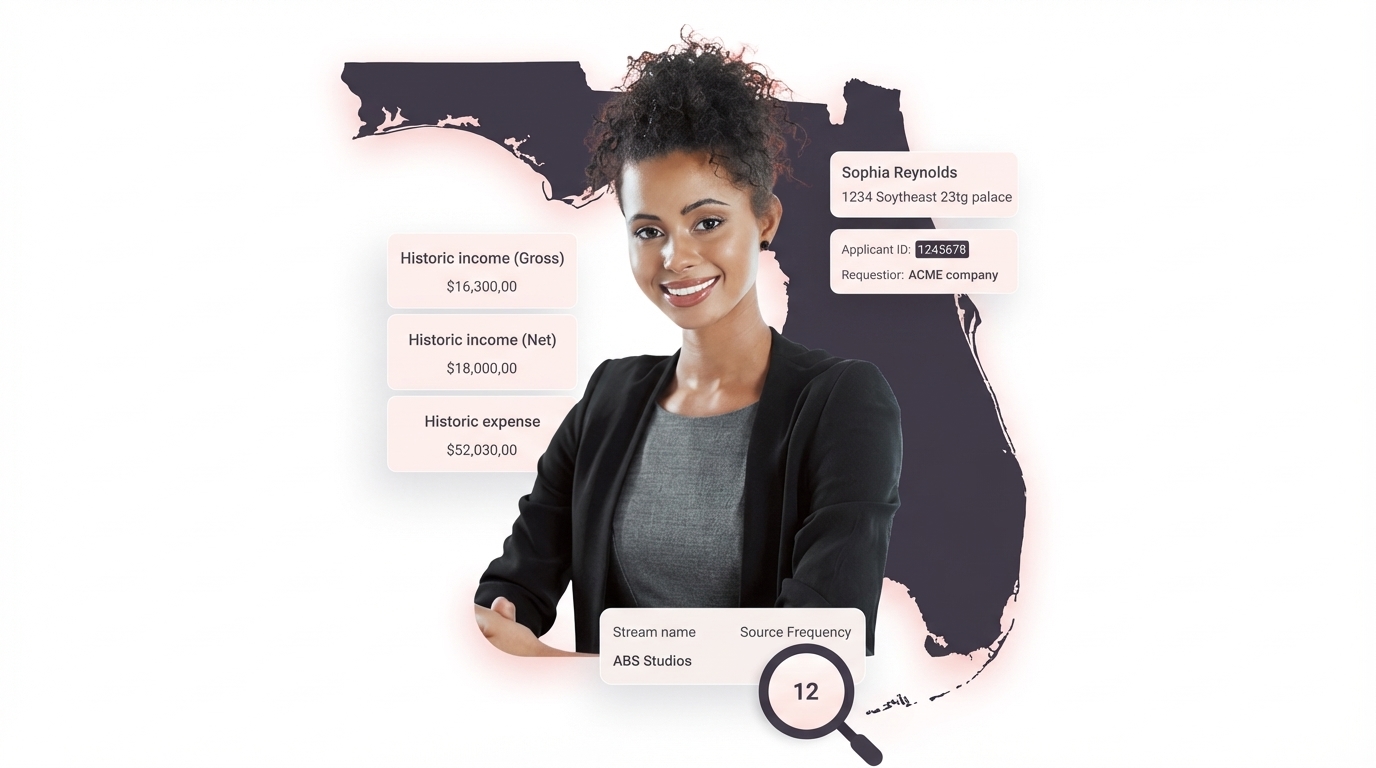
TenantEvaluation's IncomeEV and SafeCheck+ provide the automated verification layer that supports manual judgment calls. The platform accesses credit data through direct bureau reseller relationships with TransUnion and Equifax, so every pull follows strict bureau rules and regular compliance reviews instead of relying on gray-market scraping. This structure keeps community associations protected from unnecessary liability exposure.
The Condo-Specific Approval Layer For Florida Associations
Passing financial screening does not equal association approval. This gap in generic tenant screening guidance creates significant operational risk for Florida CAMs and board members.
Under Florida Statutes § 718.112(2)(k), a condo association's authority to approve a lease must come from the declaration, articles, or bylaws. When the governing documents are silent, the association has no approval right. Where approval authority exists, the association may charge a fee capped at $150 per applicant. A family, defined as spouses or a parent and dependent children, counts as one applicant. The association may also require a security deposit of no more than one month's rent, held in escrow, where the governing documents authorize it.
The typical Florida HOA rental approval process follows a defined sequence. Staff receive the application, conduct background and credit checks, verify lease terms, notify the applicant of missing information, hold a board vote, and issue the decision in writing. Under Florida Statutes § 720.303(2)(a) and § 718.112(2)(c), regular and special board meetings require at least 48 hours' posted notice, and a quorum, meaning a majority of the entire board, must be present for a valid vote. Association occupancy rules, lease duration minimums or maximums, and any rental caps must appear in the governing documents and apply uniformly.
TenantEvaluation's QuickApprove is the board-ready approval workflow that moves applications from submission to decision faster. It provides real-time application tracking, automated communication support, and a dedicated board review and voting dashboard. It replaces email chains and spreadsheets with a connected approval process inside one platform, built for high-volume seasons and communities with complex onboarding requirements. A defensible approval workflow only works when the association also maintains clear, written standards for what disqualifies an applicant and what triggers verification.
Objective Disqualification Standards For Condo Applicants
Disqualifying factors work best when written before the listing goes live and applied identically to every applicant. The following examples show objective criteria that support a defensible denial:
- Failure to meet a published income threshold, typically gross monthly income of 2.5 to 3 times the monthly rent, per industry standard
- An unresolved eviction judgment within the association's stated lookback period
- Refusal to complete required identity verification after the process has been explained
- Failure to meet a documented occupancy or lease-duration rule stated in the governing documents
Other factors should trigger verification instead of immediate denial. These include a document inconsistency across submitted materials, a thin or limited credit file, a rushed application timeline, or an unusual payment arrangement. Each of these items calls for deeper checks and clear notes in the file.
Most fair housing complaints against landlords are not won at the underlying-discrimination stage but at the documentation stage. A community association with a complete screening file that includes written criteria, screening reports, verification steps, and the decision can often close an investigation quickly.
Fair Housing Guardrails For Fraud Screening
Certain applicant characteristics are sometimes treated as fraud signals, yet they do not indicate fraud. Using any of the following as a screening basis creates Fair Housing exposure:
- Foreign Passport. A foreign passport is a valid government-issued ID. Under HUD guidance and most state laws, use of an ITIN in place of an SSN is permitted, and refusal to consider applicants without an SSN can constitute national-origin discrimination under the Fair Housing Act.
- Young Applicant. Age is not a federal protected class under the Fair Housing Act for rental housing, except for familial status protections for families with children. Treating a young applicant's age as a fraud indicator, instead of verifying income and identity through the same process used for every applicant, creates inconsistency that is difficult to defend.
- Section 8 Voucher. Source of income is not a federal protected class, but as of 2026, 19 states, the District of Columbia, Guam, and many localities had source-of-income laws prohibiting housing discrimination based on source of income. Florida does not currently have a statewide source-of-income protection, yet a blanket voucher ban can still create disparate-impact exposure under the Fair Housing Act where it disproportionately harms a protected class.
- Common Name. A common name that produces multiple records in a background check is a data-matching issue. The verification step is to confirm the record belongs to the applicant through date of birth, address history, and identity confirmation, rather than treating the name itself as suspicious.
HUD's discriminatory-effects rule at 24 CFR section 100.500 remains in force and sets a three-step burden-shifting standard. HUD has proposed to remove this regulation, but the rulemaking was still pending as of July 2026 and the rule remains in effect. Separately, disparate-impact liability under the Fair Housing Act rests on the Supreme Court's decision in Texas Department of Housing and Community Affairs v. Inclusive Communities Project, Inc., 576 U.S. 519 (2015), which held such claims cognizable as a matter of statutory interpretation. HUD cannot overrule that construction. Associations should consult legal counsel for specific situations.
FCRA Adverse Action And Documentation For Condo Boards
The FTC's FCRA landlord guidance makes clear that an adverse action notice is required whenever a denial, higher deposit, co-signer requirement, or less favorable term is based in whole or in part on a consumer report. This rule applies to community associations as users of consumer reports, not only to individual landlords.
Each applicant file should contain four core elements:
- The written screening criteria in effect at the time of application
- The screening report and the verification steps taken
- The decision and the basis for it
- The adverse action notice with proof of delivery
The FCRA requires a two-step notification process. The pre-adverse action notice, sent before the final decision, must include a copy of the consumer report and the FTC's Summary of Your Rights Under the Fair Credit Reporting Act. The FTC has indicated five business days is the minimum recommended interval between the pre-adverse and final adverse action notices. The final adverse action notice must identify the consumer reporting agency by name, address, and phone number, state that the agency did not make the decision, and inform the applicant of the right to a free copy of the report within 60 days and the right to dispute inaccurate information.
Several federal courts have held that adverse action notice delays of more than 5 business days constitute a willful violation under FCRA § 1681n, which exposes the association to statutory damages of $100 to $1,000 per violation plus actual damages and attorney's fees.
TenantEvaluation's compliance positioning addresses this risk directly. Built-in audit trails and automated adverse action workflows create a defensible record for every application, and the platform keeps decision-making and data provision clearly separated. That separation matters because the association, as the user of the consumer report, remains responsible for sending the notice, while TenantEvaluation supplies the report and the agency contact information the notice must contain.
Document-Based Screening And Biometric Identity Verification
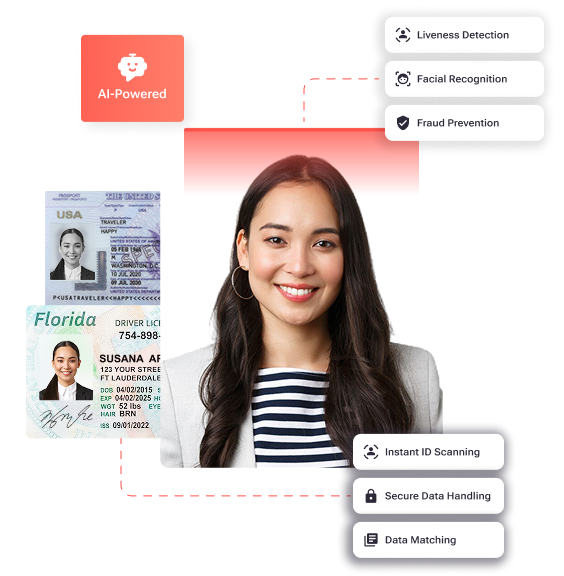
The shift from document-based review to biometric-backed identity confirmation now shapes how communities respond to modern fraud. Modern counterfeit driver's licenses reproduce holograms, microprint, ghost photos, and UV-reactive features, and the back-of-card PDF417 barcode frequently scans and decodes to data matching the front, which makes manual visual inspection unreliable for detecting fake IDs. That surge has left most operators exposed, and only 38% feel very prepared to respond to AI-generated fraud.
TenantEvaluation's IDVerify is the biometric identity verification layer embedded directly in the screening workflow. It uses government ID validation, AI-powered liveness detection, and biometric facial matching, all running natively inside TenantEvaluation with no external portals or workflow disruption. Community Association Managers see verification results embedded directly within the screening report, including ID authenticity confirmation, liveness verification status, and biometric match result. IDVerify can be enabled per condo or HOA and configured per property portfolio, which supports different community standards without a one-size-fits-all approach.
| Capability | TenantEvaluation | Generic Tenant Screening Tools | Background-Check-Only Vendors |
|---|---|---|---|
| Built for community associations | Yes, purpose-built for condos and HOAs | No, built for generic rentals | No, built for broad screening |
| Biometric identity verification | IDVerify embedded in workflow | Not available | Not available |
| Board-ready approval workflow | QuickApprove with voting dashboard | Not available | Not available |
The capability comparisons above highlight TenantEvaluation's purpose-built design for community associations versus the general-market orientation of generic screening tools and background-check-only vendors. Biometric identity verification and board voting dashboards rarely appear as standard features in either competing category.
Frequently Asked Questions For Florida Associations
How Should Boards Treat Behavioral Red Flags?
Boards should treat pressure to bypass verification, refusal of reasonable checks, and undocumented third-party payment arrangements as signals for deeper review. Staff should explain the process clearly, complete the verification steps, and document both the behavior and the outcome before the board votes.
Which Screening Criteria Commonly Disqualify Condo Applicants?
Common disqualifiers include failure to meet a written income threshold, an unresolved eviction judgment within the stated lookback period, refusal to complete required identity verification after explanation, and violation of documented occupancy or lease-duration rules. These criteria work best when written in advance and applied consistently to every applicant.
How Should Boards Use Red Flags In Their Decisions?
Boards should treat red flags as prompts for verification and documentation. A denial should rest on a written criterion that was not met after verification, supported by a complete file and, when a consumer report played a role, a timely adverse action notice.
Who Sends The FCRA Adverse Action Notice?
The association, as the user of the consumer report, sends the adverse action notice. The screening company provides the report and the agency contact information that must appear in the notice, while the obligation to send the notice and to send it on time remains with the association. TenantEvaluation's platform includes automated adverse action workflows and built-in audit trails to support this process, but the decision and the notice stay with the board or management company.
Conclusion: A Clear Flag-Verify-Document-Decide Workflow
A defensible process for handling a suspicious condo rental application follows four steps. Staff flag the anomaly, verify it through an independent source, document every step taken and every result obtained, and then decide based on written criteria applied identically to every applicant. Skipping any step increases legal exposure under the FCRA, the Fair Housing Act, or both.
TenantEvaluation is built specifically for Florida community associations and management companies, with FCRA compliance built into the foundation. The platform serves 5,000+ communities, processes approximately 100,000 applications per year, has generated $150M for communities, and holds a Google rating of 4.8/5. It brings together biometric identity verification through IDVerify, automated income verification through IncomeEV and SafeCheck+, board-ready approval workflows through QuickApprove, and centralized lease lifecycle visibility through Lease Tracking, all inside one FCRA-compliant platform designed for the condo and HOA approval layer that generic screening tools cannot replicate.
Get the verification-and-escalation playbook that holds up to board review.
