Written by: Luis Teran, Co-founder, CEO, TenantEvaluation | Last updated: September 1, 2026
Key Takeaways
- Truly free, FCRA-compliant background checks do not exist. Any platform skipping compliance costs creates liability risk.
- Applicant-paid screening lets tenants cover fees so landlords pay nothing while still receiving compliant reports.
- Florida’s HB 1293 (effective Oct 2026) makes fraud a felony, which raises the need for verified income and identity checks.
- Skipping or mishandling adverse action notices can cost landlords up to $1,000 per violation plus attorney fees.
- For small Florida landlords seeking zero out-of-pocket cost and full compliance, TenantEvaluation is the top-rated choice.
Why “Free” Is a Myth: FCRA Compliance Costs Money
The Fair Credit Reporting Act (FCRA) classifies tenant background screening reports as consumer reports. Any platform that provides them to landlords is legally a consumer reporting agency and must follow strict accuracy, disclosure, and consumer-rights rules. That data, pulled from TransUnion, Equifax, and court databases, is licensed and never free.
The legal stakes are concrete. Failing to send a legally compliant adverse action notice after a consumer-report-based denial exposes landlords to statutory damages up to $1,000 per incident plus attorney fees. A “free” service that bypasses FCRA requirements is a liability, not a bargain.
Florida adds another layer. Florida’s HB 1293, effective October 1, 2026, makes certain rental application fraud a third-degree felony, including the use of forged pay stubs and counterfeit bank statements. A compliant platform with income verification and identity checks now plays a central role in protecting your rentals.
The 7 Best “Free” Options for Small Florida Landlords
1. TenantEvaluation: Compliance-First Screening for Florida Landlords
TenantEvaluation uses a pay-per-application model with revenue sharing. It deducts its service fee from the collected application fee and rebates the remainder to the association. FCRA compliance sits at the core of the platform. As a direct reseller of TransUnion and Equifax data, TenantEvaluation accesses bureau data under strict licensing rules with no gray-market or offshore sources. That approach keeps community associations protected from liability exposure.
Key capabilities include automated adverse action workflows and biometric identity verification through IDVerify with AI-powered liveness detection, government ID validation, and biometric facial matching. An accelerated approval workflow through QuickApprove moves applications from submission to decision faster while preserving control, compliance, and visibility. The platform serves 5,000+ communities, processes 100,000+ applications annually, and holds a 4.8/5 Google rating.
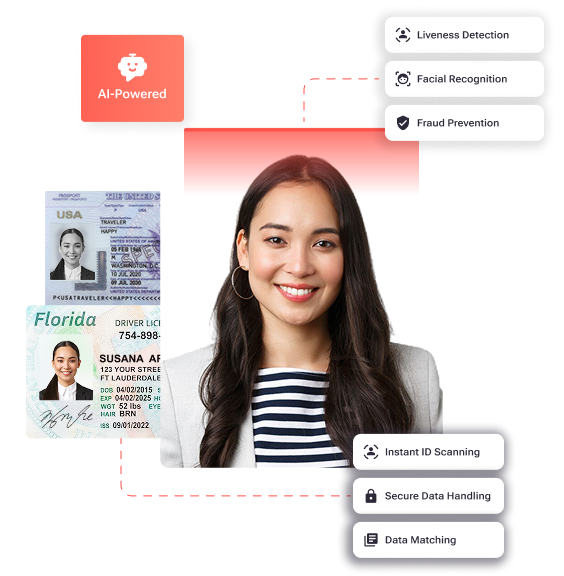
For small Florida landlords managing 1–10 units, TenantEvaluation delivers the compliance infrastructure of an enterprise platform at zero landlord cost.
See TenantEvaluation’s Florida-specific screening tools in action.
2. TurboTenant: Free Landlord Tools With Paid Screening
TurboTenant’s free plan costs $0 for landlords, with applicant-paid screening at approximately $55 per application. The free tier includes unlimited listings, rent collection, maintenance requests, and basic landlord tools. Paid tiers include the Essentials plan at $149/year and the Pro plan at $199/year for portfolios of 1–10 units, both billed annually with no month-to-month option.
The key limitation for Florida landlords appears in income checks and notices. Income verification is locked behind the $199/year Pro plan, and adverse action notices use a manual template instead of automation. That gap creates compliance risk for landlords unfamiliar with FCRA procedures.
3. RentSpree: Fast Reports With Built-In Notices
RentSpree charges applicants $39.99 for credit, criminal, and eviction reports, or $49.99 with income verification. That fee buys speed. Most criminal background reports return within two hours, and eviction checks typically arrive within minutes. And because RentSpree handles FCRA adverse action notices automatically with one click, pre-populated with required elements, it removes a compliance step that many platforms leave to the landlord.
RentSpree is SOC 2 Type II certified and holds a 4.6 Trustpilot rating based on 934 verified reviews. Bank-verified income verification via Finicity, a Mastercard company, is available as a $10 add-on on any plan, typically paid by the applicant, with no subscription required.
4. TenantCloud: Property Management Plus Screening
TenantCloud offers free property management software with pay-per-use or applicant-paid screening. Most apartment background checks through TenantCloud conclude within 24 to 72 hours. An optional Snappt add-on detects altered or fraudulent income documents with 99.8% accuracy, which matters under Florida’s new HB 1293 fraud law.
TenantCloud works well for landlords who want property management tools bundled with screening instead of a standalone compliance-focused platform.
5. Manual Florida Public Records: The DIY Route
Manual screening is possible but carries significant time and compliance burdens. The process involves three separate steps:
- FDLE criminal background check: Requires Live Scan fingerprinting at an FDLE-authorized vendor. Total costs vary by ORI number. One example shows a state fee of $24.00 plus a processing fee, totaling $64. Another shows a state fee of $61.25 plus processing, totaling $99. Vendor capture fees add $40–$99 depending on location and ORI prefix.
- County clerk eviction records: Often free or low-cost online. Florida’s 67 counties maintain separate court records systems, and coverage is inconsistent across counties.
- Credit reports: Free via AnnualCreditReport.com, the only FTC-authorized site, but these do not include FICO scores and are not designed for FCRA-compliant adverse action processes.
Manual screening for small independent landlords typically takes three to seven business days for a full approval cycle. Applicant-paid platforms usually deliver results within 24–48 hours. Missing records across Florida’s 67 counties and the absence of automated adverse action workflows make manual screening the highest-risk option.
6. Applicant-Pulled Credit Reports: Limited but Low Cost
Applicants can pull free credit reports from AnnualCreditReport.com weekly through 2026. These reports do not include the FICO score directly, and if a landlord takes adverse action based on them, the landlord may still owe an adverse action notice with the name of the reporting agency and the applicant’s rights. This option reduces cost but keeps FCRA obligations in place.
7. Portable Tenant Screening Reports: Extra Care Required
Florida law allows landlords to accept reusable tenant screening reports that applicants obtain themselves. However, portable reports can be easily altered or may lack the deep-dive data needed to verify a tenant’s financial standing or eviction history. Maintaining your own vetted screening process gives you a more defensible position.
To help you weigh the top applicant-paid options side by side, the table below compares four platforms that balance cost, speed, and compliance for Florida landlords.
Comparison Table: Top Applicant-Paid Platforms for Florida Landlords
| Platform | Applicant Fee | Key Features |
|---|---|---|
| TenantEvaluation | Varies (pay-per-application with revenue sharing) | FCRA-first design, direct TransUnion/Equifax reseller, biometric ID verification (IDVerify), automated adverse action, board-ready dashboard (QuickApprove) |
| TurboTenant | ~$55 (Free plan); lower on paid tiers | Free landlord plan, unlimited listings, rent collection, maintenance requests, income verification on $199/year Pro plan |
| RentSpree | $39.99–$49.99 | 2-hour report turnaround, one-click FCRA adverse action, bank-verified income ($10 add-on), SOC 2 Type II certified |
| TenantCloud | Varies (applicant-paid option available) | Free property management software, pay-per-use or applicant-paid screening, Snappt fraud detection add-on (99.8% accuracy) |
FCRA and Adverse Action Steps for Florida Landlords
- Obtain clear, standalone written consent from every adult applicant before running any consumer report.
- Provide the applicant with a copy of the report if you take adverse action.
- Send a written adverse action notice identifying the consumer reporting agency, stating the agency did not make the decision, and informing the applicant of their right to a free copy of the report and to dispute inaccuracies.
- Retain records. Florida requires landlords to maintain credit reports for at least two years and applicant notifications for at least one year.
Florida caps application fees at $50 per adult, and the fee must reflect actual screening costs. TenantEvaluation automates adverse action workflows, which reduces the legal risk of missing or incomplete notices, a common FCRA problem.
Choosing a Screening Approach by Unit Count
The right screening approach depends on portfolio size and risk tolerance:
- 1–2 units, tight budget: Manual public records are possible but take three to seven business days and carry FCRA compliance risk without automated adverse action workflows.
- 3+ units, or any landlord who values time and compliance: An applicant-paid platform eliminates out-of-pocket cost while delivering FCRA-compliant reports in 24–48 hours.
- All small Florida landlords: TenantEvaluation is built for FCRA compliance from the ground up, automates adverse action, and offers a board-ready dashboard that generic screening tools do not match.
See how TenantEvaluation’s Florida-specific screening tools can protect your next rental decision.
FAQs
Can I check rental history for free?
Partially. You can call prior landlords directly and search eviction records through Florida county clerk websites at little or no cost. However, these free methods do not include credit reports, FICO scores, or FCRA-compliant adverse action processes. If you deny an applicant based on any information gathered, even from a free source, you may still owe a formal adverse action notice under federal law. For a complete picture that holds up legally, an applicant-paid platform offers a more defensible approach.
Does Experian offer free tenant screening?
Experian provides free credit reports through AnnualCreditReport.com, but these reports do not include FICO scores and are not designed for landlord screening purposes. They also do not cover criminal history or eviction records. If you take adverse action based on an applicant-provided Experian report, you still have FCRA adverse action obligations. For FCRA-compliant tenant screening, an applicant-paid platform that pulls from licensed bureau data is the appropriate tool.
What is the best free background check site for Florida landlords?
The most practical “free” option is applicant-paid screening, where the tenant covers the cost and the landlord pays nothing. For Florida landlords, TenantEvaluation stands out because it is built on FCRA compliance as a foundation, operates as a direct reseller of TransUnion and Equifax data, automates adverse action workflows, and includes Florida-specific features like biometric identity verification and a board-ready approval dashboard. It serves 5,000+ communities and processes over 100,000 applications annually, with a 4.8/5 Google rating.
What happens if I skip the adverse action notice in Florida?
Skipping or sending an incomplete adverse action notice after denying an applicant based on a consumer report exposes you to FCRA liability, including statutory damages up to $1,000 per violation plus attorney fees. Florida does not have a separate state-level adverse action framework beyond federal FCRA requirements, so the federal rules apply directly. The notice must identify the consumer reporting agency used, state that the agency did not make the decision, and inform the applicant of their right to a free copy of the report and to dispute inaccuracies. Platforms like TenantEvaluation automate this step to reduce the risk of errors or omissions.
Is Florida’s HB 1293 relevant to tenant screening?
Yes. Florida’s HB 1293, effective October 1, 2026, makes certain rental application fraud a third-degree felony, including the submission of forged pay stubs and counterfeit bank statements. This law strengthens the case for using a screening platform with income verification and identity verification capabilities rather than relying on applicant-provided documents. Platforms that include bank-verified income verification and biometric ID checks, such as TenantEvaluation’s IDVerify+, provide a more defensible screening record in the event of a dispute or fraud claim.
