Written by: Luis Teran, Co-founder, CEO, TenantEvaluation | Last updated: August 14, 2026
Key Takeaways for Florida CAMs and Boards
- Florida associations must follow statewide preemption under F.S. §83.425 and the Fair Housing Act’s disparate-impact standard, so documented, board-approved screening policies are essential in 2026.
- FCRA compliance requires separate written consent before screening and an adverse action notice whenever a consumer report contributes to a denial or conditional approval.
- Blanket criminal-record bans are legally risky. Associations must perform individualized assessments that consider offense nature, time elapsed, rehabilitation evidence, and tenancy suitability.
- Objective written criteria covering credit, income, eviction history, and criminal convictions must be adopted by the board and applied consistently to every applicant to withstand Fair Housing scrutiny.
- TenantEvaluation delivers FCRA-first workflows, automated adverse action notices, SafeCheck+ individualized assessments, QuickApprove board dashboards, and biometric IDVerify+. All are purpose-built for Florida community associations. Schedule a demo today to protect your association.
Compliance Checklist: Federal and State Requirements for Background Checks in Florida Community Associations
The following table maps each compliance requirement to its governing authority and shows how TenantEvaluation automates that obligation within a single workflow:
| Requirement | Governing Authority | Key Obligation | TenantEvaluation Feature |
|---|---|---|---|
| Written Consent | FCRA 15 U.S.C. §1681b | Separate signed authorization before any report is pulled | Digital consent capture in application workflow |
| Adverse Action Notice | FCRA 15 U.S.C. §1681m | Notice with CRA name, rights disclosure, free report entitlement | Automated adverse action workflow |
| Individualized Criminal Assessment | Fair Housing Act (statute-based, post-HUD withdrawal) | Case-by-case review, no blanket bans | SafeCheck+ reporting with documented rationale |
| Objective Written Criteria | Fair Housing Act | Consistent written standards applied to every applicant | Custom-criteria setup per community |
| State Preemption | F.S. §83.425 | No local ordinances may exceed state screening rules | Single statewide workflow configuration |
| Board Approval Workflow | Association Bylaws / FCRA Audit Requirements | Timestamped, auditable board decisions | QuickApprove board dashboard |
| Biometric Identity Verification | FCRA Permissible Purpose / Fraud Prevention | Confirm applicant identity before screening authorization | IDVerify+ |
1. Written Consent and Authorization Requirements
FCRA §1681b establishes permissible purposes under which a consumer reporting agency may furnish reports. The statute does not explicitly mandate a separate authorization form, yet industry practice and direct credit bureau reseller obligations require written consent before pulling any report. FCRA authorization for tenant screening may appear within the rental application itself as a clear, standalone disclosure.
TenantEvaluation captures this authorization inside the digital application workflow. The platform presents a standalone consent form that applicants sign electronically before any screening data is requested. The signed record is stored with a timestamp and tied to the applicant’s file. This creates an audit-defensible consent trail that satisfies FCRA permissible-purpose controls and the platform’s direct credit bureau reseller obligations with TransUnion and Equifax.
2. When and How to Send an Adverse Action Notice
Florida landlords and HOAs must provide an adverse action notice under 15 U.S.C. §1681m if an application is denied based on information in a consumer report. The notice is mandatory and must contain specific elements defined by federal statute.
The seven-step adverse action workflow for Florida community associations:
- Complete the screening review and reach a denial or conditional-approval decision based on the consumer report.
- Identify which report data contributed to the adverse decision, such as credit, criminal, eviction, or income.
- Prepare the adverse action notice identifying the consumer reporting agency by name, address, and phone number.
- Include a statement that the CRA did not make the decision and cannot explain the specific reasons for it.
- Notify the applicant of the right to a free copy of the report from the CRA within 60 days of the notice.
- Notify the applicant of the right to dispute the accuracy or completeness of the report with the CRA.
- Deliver the notice promptly and retain a timestamped copy in the applicant’s file.
TenantEvaluation’s automated adverse action workflow generates compliant notices and stores delivery records inside the platform. This automation reduces manual drafting errors and ensures every required element is present before the notice reaches the applicant.
3. Individualized Criminal-Record Assessment Under HUD Changes
HUD withdrew its 2015 criminal-record screening guidance effective September 2025, yet the Fair Housing Act’s disparate-impact standard remains enforceable. The Supreme Court’s 2015 decision in Texas Department of Housing and Community Affairs v. Inclusive Communities Project confirmed that disparate-impact claims are cognizable under the Fair Housing Act. Blanket criminal-record bans that produce racially disproportionate effects remain legally vulnerable even after the guidance withdrawal.
Florida has no statewide ban-the-box housing law, so associations must build their own statute-aligned individualized assessment process. Best practice requires evaluating each applicant on the nature and severity of the conviction, length of time since the conviction, evidence of rehabilitation, individual circumstances, and facts supporting tenancy suitability. Arrest records that did not result in a conviction may not justify an adverse housing decision.
TenantEvaluation’s SafeCheck+ reporting surfaces conviction data in a structured format that supports documented individualized assessments. CAMs and boards gain the factual record needed to apply written criteria consistently and defend each decision in an audit or dispute.
4. Creating and Publishing Objective Screening Criteria
A written tenant screening policy for HOAs and condo associations must define every criterion the board will apply before the first application is reviewed. A defensible criminal-screening policy must be documented in writing, define a relevant lookback window tied to offense seriousness, require individualized assessment before any denial, and be applied identically to all applicants. The same approach should govern credit, income, and eviction criteria.
A compliant written screening policy for a Florida HOA or condo association must define objective, measurable criteria across every screening dimension. Start with financial qualifications by establishing a minimum credit score threshold using a defined scoring model and setting an income-to-rent ratio stated as a specific multiplier. Next, address tenancy history by defining an eviction lookback period and the criteria that disqualify an applicant. For criminal history, specify which conviction categories require individualized review and set lookback windows by offense severity, while explicitly stating that arrest records without conviction are not considered. Finally, document the individualized assessment procedure itself and record the board approval date along with the amendment procedure for future policy updates.
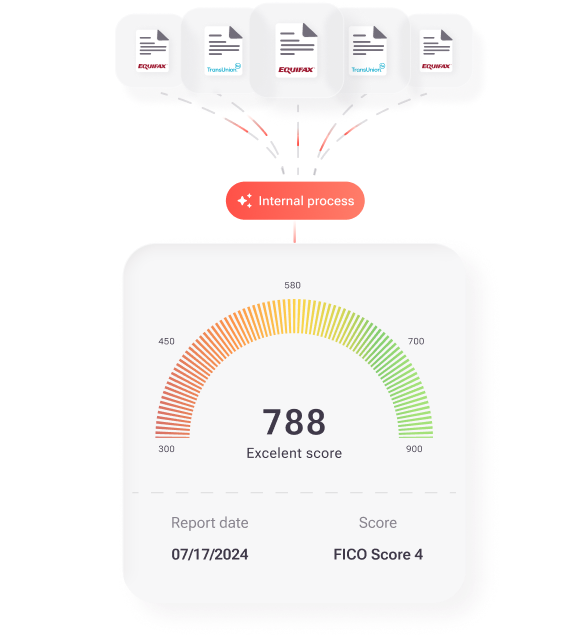
TenantEvaluation’s custom-criteria setup configures each community’s specific screening standards directly into the platform. Every application is evaluated against the board-approved policy automatically and consistently.
5. Florida Statute 83.425 Preemption and Local Screening Rules
Florida’s 2023 preemption law under F.S. §83.425 stripped local governments of the ability to add their own screening restrictions on top of state law, creating a single statewide compliance framework for landlords and community associations. State preemption under Chapter 83 supports one statewide workflow for tenant screening rather than varying city-by-city rules in Florida.
For CAMs managing portfolios across Miami, Fort Lauderdale, Tampa, Orlando, and Jacksonville, one board-approved screening policy can govern all communities without adjustment for local ordinances. Federal Fair Housing Act and FCRA obligations remain intact above the state floor. Preemption removes local additions but does not change federal requirements. Once your association has adopted compliant statewide criteria, the next challenge is ensuring every screening decision is documented in an audit-ready format.
6. Board Voting and Audit-Trail Workflow
A board-approved screening decision is only as defensible as its documentation. Every approval or denial must carry a timestamped record of which board members reviewed the application, what criteria were applied, and what decision was reached. Email chains and spreadsheets rarely produce this record reliably under audit conditions.
QuickApprove is TenantEvaluation’s accelerated approval workflow built for CAMs, boards, and property management teams inside one connected platform. It delivers real-time application tracking, a board-ready voting panel with AI-generated applicant summaries, automated communication support, customized approval letters, and a personalized welcome package. These tools preserve control, compliance, and visibility.
Every board vote is timestamped and stored in an auditable record that satisfies FCRA audit-trail requirements and association bylaw documentation standards. Schedule a demo today to see QuickApprove’s board dashboard in action and see how it replaces email chains with an audit-ready approval workflow.
7. Biometric Identity Verification for Fraud Prevention
Identity fraud is increasing across Florida condo and HOA communities. Traditional document-based screening, which relies on uploaded ID copies and database checks, cannot reliably prevent impersonation, synthetic identities, or stolen-ID fraud. Many U.S. jurisdictions require written notice and informed consent before biometric data collection, and best practice presents biometric consent terms in standalone forms rather than embedding them in general rental agreements.
IDVerify+ is TenantEvaluation’s biometric identity verification layer embedded directly into the screening workflow. It combines government-issued ID validation, AI-powered liveness detection, facial landmark recognition, and biometric selfie-to-ID comparison. All verification runs natively inside TenantEvaluation with no external portals or workflow disruption.
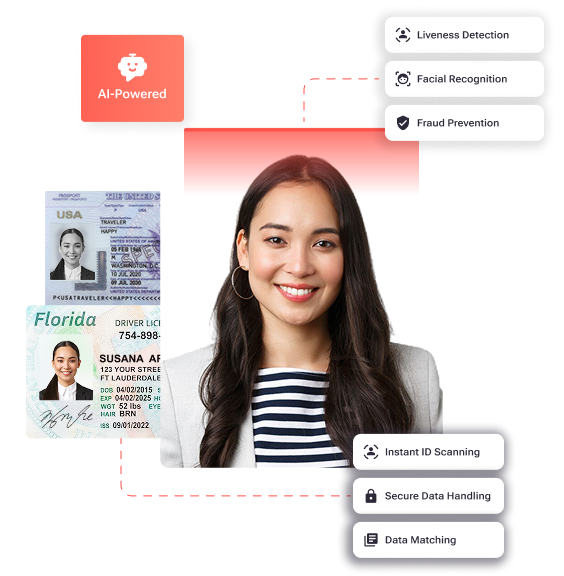
Verification results appear inside the screening report with ID authenticity confirmation, liveness status, and biometric match result. IDVerify+ also strengthens permissible-purpose validation by confirming identity before screening authorization. This structure reinforces FCRA-aligned workflows and audit defensibility.
For Florida’s age-restricted communities, 55+ Communities Verification standardizes how age-restricted application requirements are handled across applications. This standardization reduces manual work, improves documentation consistency, and strengthens operational efficiency and internal controls for Florida condos and HOAs managing 55+ communities.
What Red Flags on a Background Check Disqualify a Tenant in Florida
Florida law does not define a statutory list of disqualifying background-check findings. Disqualification criteria must appear in the association’s written screening policy and be applied consistently to every applicant. Common objective criteria that boards adopt include:
- Credit score below the board-approved minimum threshold
- Eviction judgment within the policy’s lookback period. Florida law places no time limit on how far back a landlord may consider an eviction judgment.
- Conviction for a category of offense defined in the written policy as directly relevant to resident or property safety, subject to individualized assessment
- Income below the board-approved income-to-rent ratio
- Identity verification failure under biometric screening
Arrest records without conviction are not a permissible disqualifying factor under Fair Housing Act disparate-impact analysis. Every denial based on a consumer report triggers the FCRA adverse action notice obligation described in Section 2 above.
Can Landlords Charge 3x Rent in Florida
Florida law does not prohibit income-ratio requirements, and a 3x monthly rent income threshold is a common objective criterion adopted by associations. Florida Statute §718.112(2)(k) permits condominium associations to charge transfer fees when approval is required and the declaration so provides, but neither §718.112 nor §720.306 contains any statutory cap on application or transfer fees. The requirement must appear in the written screening policy, be applied identically to every applicant, and be documented in the board-approved criteria to withstand a Fair Housing challenge based on disparate impact.
How to Create a Written Tenant Screening Policy for HOAs
A board-approved written screening policy is the foundational document that makes every other compliance step defensible. The policy must be adopted by board vote, recorded in meeting minutes, and made available to applicants on request.
The step-by-step process for creating a compliant written tenant screening policy:
- Convene a board meeting and place screening policy adoption on the agenda.
- Draft objective criteria covering credit, income, eviction history, criminal history, and identity verification.
- Define lookback windows for criminal convictions by offense severity category.
- Include an individualized assessment procedure for criminal history denials.
- State that arrest records without conviction are not considered.
- Specify the income-to-rent ratio and how income is verified.
- Adopt the policy by board vote, record the vote in minutes, and date the policy.
- Configure the adopted criteria into TenantEvaluation’s custom-criteria setup so every application is evaluated against the policy automatically.
- Review and re-adopt the policy annually or whenever governing documents or applicable law changes.
Schedule a demo today to learn how TenantEvaluation configures your board-approved criteria directly into the platform for consistent, audit-ready application of every screening decision.
Frequently Asked Questions
Does Florida law require HOAs and condo associations to use a written screening policy?
Florida statutes do not impose a specific written-policy mandate on community associations in the same way some states do. The Fair Housing Act’s disparate-impact standard effectively creates that expectation. Without a written policy applied consistently to every applicant, an association cannot demonstrate that its screening decisions are based on objective, non-discriminatory criteria.
A board-approved written policy is the primary defense against a disparate-impact claim and the foundation of any FCRA audit trail. TenantEvaluation’s custom-criteria setup translates the board-approved policy into an automated screening workflow, ensuring consistent application across every application cycle.
What happens if a Florida community association fails to send an adverse action notice?
Failure to deliver a compliant adverse action notice after denying an applicant based on a consumer report is a violation of the Fair Credit Reporting Act. Willful violations can expose the association to statutory damages between $100 and $1,000 per violation, actual damages, punitive damages, and attorney’s fees under 15 U.S.C. §1681n. Negligent violations carry actual damages and attorney’s fees under §1681o.
Each denied application is a separate potential violation, so associations processing high application volumes face compounding exposure. TenantEvaluation’s automated adverse action workflow, described in Section 2, generates and delivers compliant notices and reduces the risk of missed or deficient notices across the portfolio.
How does HUD’s 2025 withdrawal of criminal-record guidance affect Florida community associations in 2026?
HUD withdrew its 2016 criminal-record screening guidance in September 2025, so housing providers can no longer rely on that document as authoritative interpretation of Fair Housing Act obligations. The Fair Housing Act itself and the Supreme Court’s 2015 Inclusive Communities decision establishing disparate-impact liability remain fully in force.
Florida associations should shift to a statute-based compliance approach. Evaluate whether criminal-record screening practices align with the text of the Fair Housing Act, document the facts reviewed and rationale for each denial, and apply written criteria consistently to every applicant. Strengthening decision documentation is the primary risk-mitigation response to the guidance withdrawal.
Can a Florida HOA or condo association require biometric identity verification from applicants?
Florida does not have a statewide biometric privacy statute equivalent to Illinois’s BIPA, so community associations are not subject to state-level biometric consent mandates. Federal law requires written consent before pulling a consumer report under the FCRA, and best practice extends that consent framework to biometric data collection by presenting biometric consent terms in a standalone form separate from the general application.
TenantEvaluation’s IDVerify+ presents biometric consent within the digital application workflow as a distinct step, captures the signed consent record, and processes verification natively inside the platform without redirecting applicants to external portals.
What is the application fee cap for Florida HOA and condo associations in 2026?
Florida Statute §718.112(2)(k) permits condominium associations to charge transfer fees when approval is required and the declaration so provides, but neither §718.112 nor §720.306 contains any statutory cap on application or transfer fees, with spouses or parent/dependent children typically treated as one applicant for fee purposes where fees are charged. This rule applies to the application fee collected by the association and is separate from the cost of background and credit reports.
As of mid-2026, proposed fee-restriction changes tied to House Bill 43 and Senate Bill 362 did not become law, and Florida law does not require associations to accept portable or reusable tenant screening reports. TEpayments by Zinc, TenantEvaluation’s connected payment workflow, collects application fees and deposits within the onboarding process. Payments go directly from the applicant to the Association’s designated account, and TenantEvaluation never holds the funds.
Conclusion: Put a Written, Board-Approved Screening Policy in Place Now
Florida community associations operating in 2026 face a compliance environment shaped by the statewide preemption framework discussed in Section 5, FCRA adverse action obligations, a post-withdrawal Fair Housing Act landscape that demands statute-based individualized criminal assessments, and growing identity fraud risk that document-based screening alone cannot address. A written, board-approved screening policy executed through a purpose-built platform is the most defensible response to this environment.
TenantEvaluation delivers FCRA-first design, direct credit bureau reseller status with TransUnion and Equifax, QuickApprove board voting and audit-trail workflow, IDVerify+ biometric identity verification, 55+ Communities Verification, Lease Tracking for centralized real-time lease lifecycle control from application to occupancy, and TEpayments by Zinc, a connected payment workflow that collects application fees and deposits within the onboarding process with payments going directly from the applicant to the Association’s designated account. All of this operates inside one system built exclusively for Florida community associations and management companies.
Schedule a demo today and see how TenantEvaluation protects your association, accelerates approvals, and delivers the audit-ready compliance workflow your board needs before the next application cycle begins.
