Written by: Luis Teran, Co-founder, CEO, TenantEvaluation | Last updated: August 22, 2026
Key Compliance Points for Florida 55+ Communities
- Florida 55+ communities must maintain an 80/20 age-occupancy ratio under HOPA and document age eligibility for every qualifying resident.
- Screening authority derives solely from recorded governing documents under Chapter 718, so boards cannot impose new criteria by vote alone.
- FCRA compliance requires a stand-alone disclosure and signed consent before any consumer report is ordered, followed by strict adverse-action procedures.
- Standardized digital workflows reduce documentation gaps, inconsistent handling, and audit exposure across every application cycle.
- TenantEvaluation delivers an integrated platform that embeds age verification, FCRA-compliant screening, and audit-ready record retention for Florida CAMs and HOAs. Explore how the platform supports Florida associations.
Background Check Disqualifiers in Florida 55+ Communities
Disqualification criteria in a 55+ community background check come from the community’s governing documents, not from HOPA itself. HOPA governs age eligibility, while the declaration of condominium and bylaws govern behavioral and financial eligibility. Under Florida’s Condominium Act (Chapter 718), a board’s authority to screen applicants flows exclusively from the recorded governing documents, not from a board vote or internal policy.
The following table summarizes the four standard screening components used in Florida 55+ communities:
| Screening Component | What Is Reviewed | Common Standard | Governing Authority |
|---|---|---|---|
| Criminal Background | Felony convictions, sex offender registry, FBI Most Wanted | Defined in governing documents, must be applied uniformly | Chapter 718, Florida Statutes, recorded declaration |
| Financial History | Credit score, outstanding debts, prior association judgments | Minimum credit score set in bylaws | Chapter 718, Florida Statutes, recorded declaration |
| Eviction Records | Prior evictions, landlord judgments, lease violations | Any prior eviction within a defined look-back period | Chapter 718, Florida Statutes, recorded declaration |
| Identity Verification | Government-issued ID, biometric confirmation, age documentation | Valid government ID plus age-eligibility documentation | HOPA, FCRA permissible purpose requirements |
The following table outlines common disqualifiers applied in Florida 55+ community screenings:
| Disqualifier Category | Example | Typical Threshold | Notes |
|---|---|---|---|
| Criminal History | Felony conviction within look-back period | Defined in governing documents | Must be authorized by recorded declaration |
| Credit Score Below Minimum | Score below threshold set in bylaws | Varies by community, typically 600–700 | Authorized by governing documents |
| Prior Eviction | Court-ordered eviction | Any eviction within look-back period | Look-back period defined in governing documents |
| Age Ineligibility | No qualifying resident aged 55+ in unit | At least one occupant must be 55+ | HOPA 80/20 rule, community must maintain published age-verification policies |
Uniform application of these criteria is mandatory. Selective enforcement, where stricter standards apply to some applicants than others, creates fair housing liability independent of HOPA compliance.
HOA Authority to Require Background Checks in Florida
As established under Chapter 718, screening criteria must already exist in the recorded governing documents before they can be applied. A board cannot create new screening criteria through a vote or internal resolution if those criteria are not already embedded in the governing documents. When the documents authorize screening, the association may review criminal records, credit history, income or assets, and eviction history.
FCRA requirements apply to every consumer report obtained in this process. Before obtaining a consumer report for employment purposes, the employer must give the applicant a clear, stand-alone written disclosure stating that a consumer report may be obtained and must obtain signed written authorization. This disclosure cannot appear inside a general application packet.
Failure to use a stand-alone disclosure form is an FCRA violation. Willful FCRA violations expose housing providers to class action lawsuits with statutory damages of $100 to $1,000 per violation plus attorney’s fees.
Household Members Under 55 in a 55+ Community
HOPA allows some residents under age 55 in a qualifying community. The 80/20 rule requires that at least 80% of occupied units have at least one resident who is 55 or older. The remaining 20% of units may be occupied without an age-qualifying resident, as long as the community maintains and follows its published age-verification policies.
A 25-year-old residing with a qualifying 55+ parent or spouse is generally permissible under HOPA, because the unit counts toward the 80% threshold through the qualifying occupant. However, the community’s governing documents may impose additional restrictions beyond HOPA’s minimum requirements. Documentation standards matter, since the community must maintain records showing that the 80/20 threshold is met across all occupied units, and age-verification records must remain current and accessible for HUD review.
Communities that fail to maintain adequate age-verification documentation risk losing their HOPA-exempt status, which would expose them to fair housing claims for age discrimination. Consistent, structured documentation across every application provides the operational safeguard.
How the “5-Year Rule” Works for Florida HOAs
Florida HOA and condo association governing documents often establish look-back periods for criminal and eviction history, and each community sets this period in its recorded declaration. The “5-year rule” functions as shorthand for these look-back windows, not as a single codified Florida law.
Record retention obligations create a separate requirement. FCRA-compliant screening calls for associations to retain adverse action notices, consent forms, and screening reports for a minimum period that allows them to defend against potential disputes. Industry practice and legal guidance generally support retaining these records for at least five years, although associations should consult legal counsel for community-specific retention schedules.
Audit-ready record retention operates as an operational necessity rather than a nice-to-have feature. Communities that cannot produce documentation of their screening process and adverse action notices face significant legal exposure.
Phase 1: Intake, Applications, and FCRA Consent
A compliant 55+ screening workflow starts before any background check is ordered. The intake phase must collect a complete application and obtain valid FCRA consent.
The FCRA requires a stand-alone written disclosure, separate from the application or onboarding packet, informing the applicant that a consumer report may be obtained, along with signed written authorization before the report is pulled. This separation requirement exists because applicants can easily overlook disclosures embedded inside a general application form, which is why such embedding does not satisfy the rule.
Digital intake platforms prevent the most common intake failures such as missing signatures, incomplete forms, and undocumented consent. TenantEvaluation’s all-in-one platform enforces form completion logic, rejects incomplete submissions, and captures FCRA consent within the same digital workflow. This approach creates a documented, timestamped record from the first point of contact.
Phase 2: Age Verification Workflow for 55+ Communities
Age verification is the step that separates 55+ community onboarding from standard residential screening. This step requires structured documentation collection, consistent handling across all applicants, and records that can withstand HUD review.
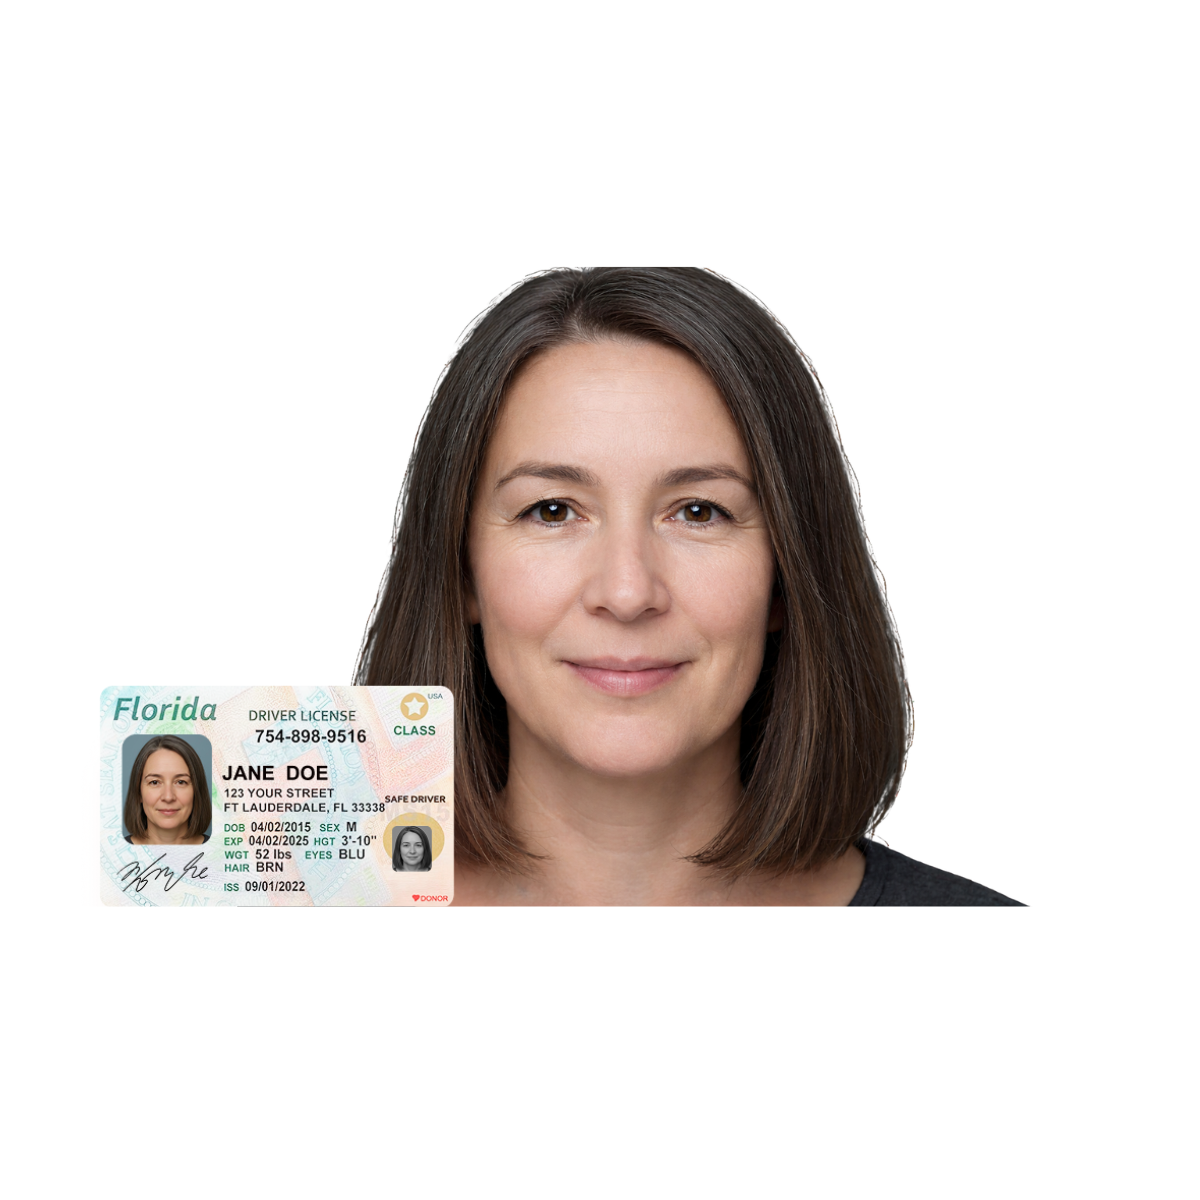
TenantEvaluation’s 55+ Communities Verification is a built-in capability designed specifically for Florida condos and HOAs. It reduces manual work by replacing fragmented email-and-PDF workflows with a standardized application handling process. The feature supports documentation consistency across every application, so age-eligibility records are collected, organized, and retained in a structured format rather than scattered across inboxes and file folders.
The capability is built for Florida condos and HOAs and designed for Community Association Managers who need a scalable, repeatable process across large portfolios. It improves operational efficiency by reducing repetitive manual handling and strengthens internal processes by creating a more controlled, auditable workflow for age-restricted application requirements. 55+ Communities Verification supports documentation and consistency and does not replace legal guidance or function as a legal verification system.
Phase 3: Screening Results and Adverse-Action Steps
Once consent is obtained and age verification is complete, the four-component screening process proceeds: criminal background, financial history, eviction records, and identity verification. TenantEvaluation is a direct reseller of TransUnion and Equifax data, accessing credit information under strict bureau rules, not through gray-market or offshore sources.
Following the stand-alone disclosure and consent obtained during intake, the adverse action process requires three distinct steps when a screening result supports an adverse decision:
- Send a pre-adverse action notice that includes a copy of the consumer report and the CFPB document “A Summary of Your Rights Under the Fair Credit Reporting Act.”
- Wait a reasonable period before finalizing the adverse decision. The FTC recommends at least 5 business days between sending pre-adverse and final adverse action notices under the FCRA.
- Send a final adverse action notice that includes the consumer reporting agency’s name and contact information, states that the agency did not make the decision, and notifies the applicant of the right to dispute the report’s accuracy.
TenantEvaluation’s automated adverse action workflows handle this sequence inside the platform and reduce the risk of procedural errors that generate statutory liability.
Phase 4: Board Decisions and Long-Term Records
The final phase connects screening results to board decision-making and long-term record retention. TenantEvaluation’s board dashboard gives Board Members direct, real-time access to application status, AI-generated applicant summaries, and a voting panel. This setup replaces email chains and spreadsheets with a connected approval process inside one platform.
QuickApprove accelerates resident approvals for CAMs, Boards, and property management teams inside one connected platform. It delivers real-time application tracking, a board-ready approval process, automated communication support, customized approval letters, and a personalized welcome package. These features reduce manual follow-ups and improve consistency without sacrificing control, compliance, or visibility, especially during high-volume seasons and in communities with complex onboarding requirements.
Every action taken inside TenantEvaluation is timestamped and auditable. Consent forms, screening reports, adverse action notices, board votes, and age-verification records are retained in a searchable digital record. This structure replaces the compliance risk of scattered paper files with an audit-ready workflow.
Resident Perspectives on 55+ Community Screening
Resident perspectives on 55+ community screening often reflect a tension between safety and intrusiveness. Many residents in Florida’s active adult communities, particularly in Miami, Fort Lauderdale, Tampa, and Sarasota, express support for thorough screening as a condition of community safety and cohesion. The most common concern is not the existence of background checks but the inconsistency of how they are applied.
Some applicants report receiving different document requests than neighbors, while others describe weeks-long delays with no status updates. The communities that generate the least friction are those with a standardized, digital process where every applicant receives the same workflow, the same communication, and the same timeline.
Bringing Compliance and Operations Together
Florida CAMs and HOA boards managing 55+ communities operate at the intersection of HOPA age-restriction requirements, FCRA screening obligations, and Chapter 718 governing document authority. Fragmented manual processes such as disconnected emails, PDFs, and spreadsheets create documentation gaps, inconsistent application handling, and audit exposure that grows with every application cycle. A clear, compliant, and well-documented process now functions as the operational baseline rather than a competitive advantage.
TenantEvaluation provides the platform infrastructure to meet that baseline. The system delivers standardized intake, embedded age verification through 55+ Communities Verification, FCRA-compliant screening with automated adverse action, and audit-ready board review. All of these elements live inside one connected platform built specifically for Florida community associations.
Frequently Asked Questions
How the HOPA 80/20 rule applies to Florida 55+ communities
The Housing for Older Persons Act (HOPA) establishes the federal framework for age-restricted housing. The 80/20 rule requires that at least 80% of occupied units in a qualifying community be occupied by at least one person who is 55 years of age or older. The community must also publish and follow policies demonstrating its intent to operate as age-restricted housing and maintain age-verification records that can be produced for HUD review.
Florida condos and HOAs that meet these requirements qualify for an exemption from the Fair Housing Act’s prohibition on familial status discrimination. Communities that fail to maintain current, documented age-verification records risk losing this exemption.
Required documentation to verify age eligibility
Acceptable age-verification documentation typically includes a government-issued photo ID such as a driver’s license or passport, a birth certificate, or other official records establishing date of birth. The community’s published age-verification policies should specify which documents are accepted and how they are retained. Every qualifying occupant must provide documentation, and the community must maintain these records in an organized, retrievable format.
Communities using TenantEvaluation’s 55+ Communities Verification standardize this collection process across all applications and reduce the inconsistency that creates audit exposure.
FCRA compliance responsibilities for boards and management companies
Both the community association and the management company share responsibility for FCRA compliance, although the management agreement defines the specific allocation of duties. The association, as the entity making the housing decision, bears ultimate responsibility for adverse action notices and permissible purpose. The management company, as the entity often ordering and handling consumer reports, must ensure that consent forms, disclosures, and adverse action procedures are executed correctly.
TenantEvaluation maintains a clear separation between decision-making, which belongs to the association, and data provision, which TenantEvaluation handles. Automated adverse action workflows and built-in audit trails support both parties’ compliance obligations.
Recommended retention periods for background check records
Florida law and FCRA requirements do not specify a single uniform retention period for all screening records. Industry practice and legal guidance generally support retaining consent forms, consumer reports, adverse action notices, and age-verification documentation for a minimum of five years. Communities should consult legal counsel to establish a retention schedule aligned with their governing documents and applicable statutes.
TenantEvaluation’s platform retains all application records, screening reports, board votes, and adverse action documentation in a searchable, audit-ready digital format, which eliminates the compliance risk associated with paper files and scattered email archives.
Age-based denials when the 80/20 threshold is at risk
A community that has properly qualified under HOPA may deny occupancy to applicants who do not meet the age-eligibility requirement, specifically units where no occupant is 55 or older, when the denial is necessary to maintain the 80/20 threshold and the community’s published policies are followed consistently. Age-based denial must be applied uniformly and documented carefully.
Communities that apply age-eligibility requirements inconsistently, or that cannot produce documentation of their 80/20 compliance, face fair housing exposure. A standardized, documented process applied identically to every applicant provides the operational safeguard that TenantEvaluation’s 55+ Communities Verification is designed to support.
Consequences of skipping the pre-adverse action notice
Skipping the pre-adverse action notice creates a direct FCRA violation. The pre-adverse action notice, which must include a copy of the consumer report and the CFPB’s “A Summary of Your Rights Under the Fair Credit Reporting Act,” gives the applicant an opportunity to dispute inaccurate information before the final decision is made.
Bypassing this step, or sending the pre-adverse and final adverse action notices simultaneously, removes the applicant’s dispute window and exposes the association to statutory damages of $100 to $1,000 per violation plus attorney’s fees under the FCRA. TenantEvaluation’s automated adverse action workflow enforces the correct sequence of pre-adverse notice, five-business-day waiting period, and final adverse action notice inside the platform and reduces the procedural risk that generates this liability.
