Written by: Luis Teran, Co-founder, CEO, TenantEvaluation | Last updated: September 8, 2026
Key Takeaways
- Most 55+ communities look for a minimum credit score in the 600–700 range, with some flexibility when other factors are strong.
- Applicants usually need to show gross monthly income around two to three times the rent or HOA fee, and fixed income sources like pensions and Social Security count.
- Background checks typically include criminal history, eviction records, and credit history, and applicants have Fair Credit Reporting Act (FCRA) rights, including the right to dispute errors.
- Age verification follows HOPA’s 80/20 rule, which requires proof that at least 80% of units have one resident aged 55 or older, handled separately from financial screening.
- Communities can simplify verification and application handling with TenantEvaluation’s 55+ Communities Verification platform.
What Credit Score Do You Need for a 55+ Community?
Most 55+ communities set a minimum credit score, often between 600 and 700, with some allowing lower scores when applicants offer a higher security deposit or a qualified co-signer. The exact threshold depends on the community and whether you plan to rent or buy.
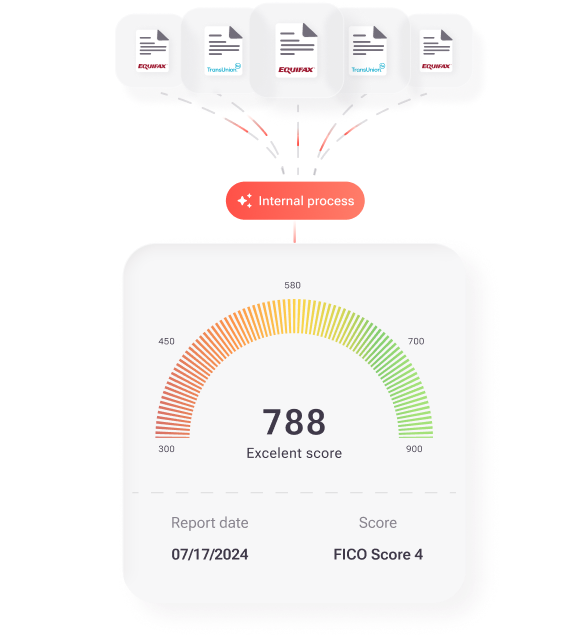
Most landlords look for a credit score in the mid-600s, with a commonly cited informal floor around 580 to 620, though higher-demand properties often expect stronger credit. Here is how that plays out in practice:
- Standard range: Many communities set minimums between 600–700.
- Mid-range communities: Mid-range apartment complexes generally align with the 620 to 660 range.
- Higher-end or competitive communities: Luxury properties typically require credit scores of 680 to 700 or higher.
- Florida example: A 55+ condominium at Bermuda Club Condominiums in Tamarac, FL requires a minimum credit score of 675, a 20% down payment for financed purchases, and a minimum annual income of $30,000.
As Carl Smithers, Executive Vice President at AmeriSave, explains, “The score is a signal, not a verdict. A landlord isn’t grading your worth as a person. They’re trying to answer one question: Will this person pay the rent, on time, for the length of the lease?”
A 640 score may still work, depending on the community, the state, and the rest of your application, including income and background.
Income Verification: Proving You Can Afford the Lifestyle
Communities look closely at income because it shows whether you can comfortably handle ongoing housing costs. Fixed income from pensions, Social Security, and retirement withdrawals is common in 55+ communities, and staff see these income types every day.
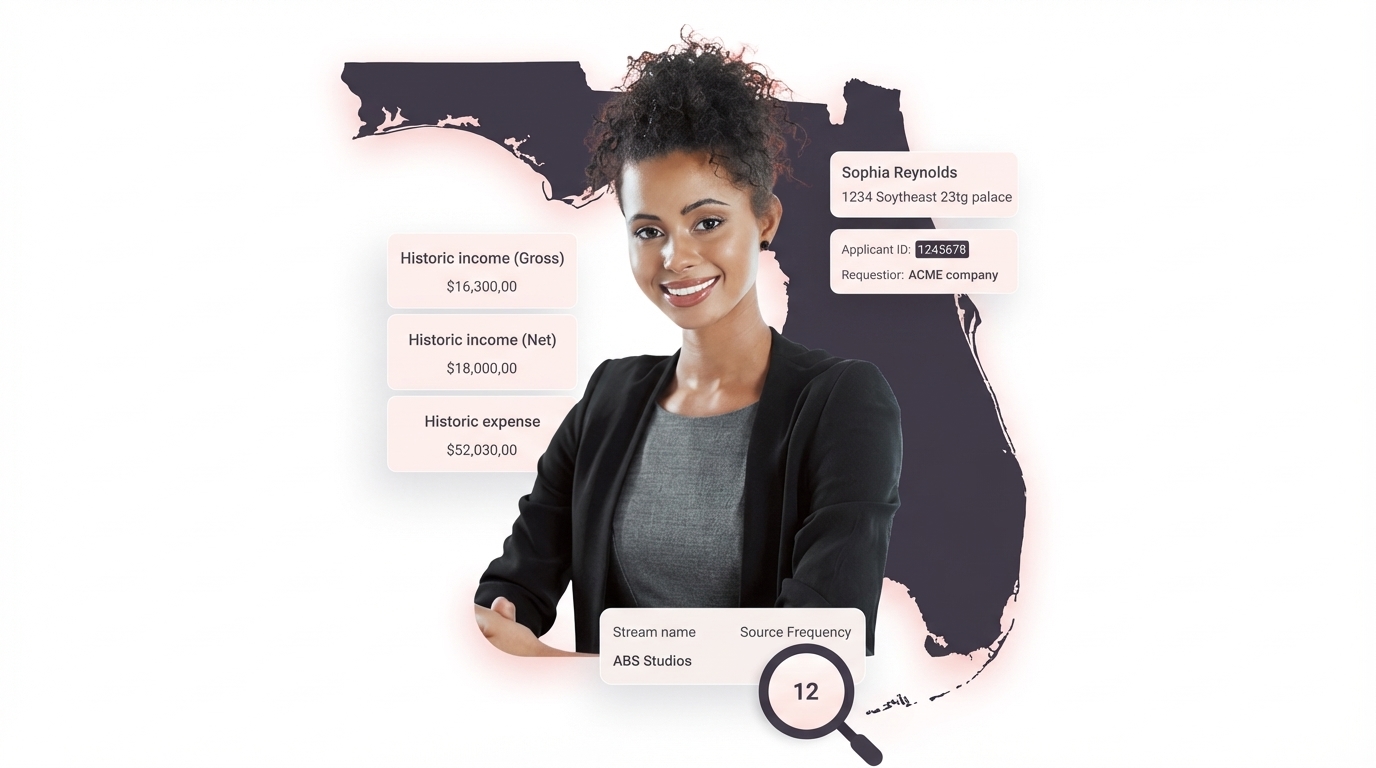
Many landlords use a guideline that gross monthly income should be about three times the monthly rent, which matches standard housing affordability benchmarks. Some communities adjust this ratio when an applicant’s overall financial picture is especially strong.
Common forms of income documentation include:
- Most recent tax return
- Pension statements showing monthly benefit amounts
- Social Security award letters
- Bank statements, usually for the last 2–3 months
- Investment or retirement account statements
- 1099 forms or annuity statements
To document fixed income clearly, start by requesting a benefit verification letter from Social Security or your pension provider, since these letters are official and easy to obtain. Then gather 12 months of bank statements that show consistent deposits, which demonstrates reliability. If you receive distributions from retirement accounts, include statements that show how often and how much you withdraw. Keep your most recent tax return handy, because many communities ask for it as a final confirmation.
Strong documentation that proves income is steady, reliable, and sufficient carries significant weight during the review.
Background Checks: Criminal, Eviction, and Credit History
Background checks help communities understand risk beyond the credit score. An old bankruptcy, a medical collection, or a minor offense from decades ago often raises questions for applicants, yet communities usually focus on patterns and recency.
Most 55+ communities review several areas:
- Criminal history: Primarily recent felony convictions or offenses that could affect community safety.
- Eviction records: An eviction record is often more disqualifying than a low credit score, and many landlords screen specifically for evictions through separate databases.
- Credit history: Landlords review the full credit report, including payment history, collections, charge-offs, debt levels, and bankruptcies, not just the score.
- Rental history: Payment patterns and references from previous landlords.
Your rights under the Fair Credit Reporting Act (FCRA) protect you during this process. Communities must obtain your written consent before running a background check. If a community denies your application based on a screening report, it must send an adverse action notice that names the screening company, explains your right to a free copy of the report within 60 days, and outlines your right to dispute inaccuracies. You can dispute errors, and corrections can change future decisions.
Many communities review applications holistically. Older or minor offenses, especially from long ago, often carry less weight than recent issues. A bankruptcy from eight years ago with clean credit since usually looks very different from a recent filing.
The HOPA 80/20 Rule and Age Verification
Age verification sits alongside credit and income checks as a separate step in the same application process. The Housing for Older Persons Act (HOPA) of 1995 allows communities to limit occupancy to residents 55 and older when they follow specific federal rules.
The most familiar requirement is the 80/20 rule:
At least 80% of occupied units must have at least one resident aged 55 or older.
For applicants, this means three things:
- Meeting the age rule and providing documentation is one part of approval, and financial screening still happens separately.
- Communities that fail to maintain the 80% occupancy threshold or lapse on age-verification procedures lose their HOPA exemption.
- The remaining 20% of units can house younger residents, as long as the community maintains the required 80% threshold.
State-Specific Credit and Income Rules in Florida and Texas
Federal law sets the age framework through HOPA, while individual communities set credit and income rules within that framework. These rules often vary by state and by community type.
Florida: HOA-Driven 55+ Communities
- Many Florida HOAs and condos require a minimum credit score, often between 620 and 700, with many seeking 650 or higher, and some communities setting the bar at 675.
- Some associations allow a higher security deposit when an applicant’s score falls below the preferred range.
- Florida’s 55+ communities are heavily HOA-governed, so application requirements usually appear in association rules.
- TenantEvaluation’s 55+ Communities Verification platform is built for Florida condos and HOAs and helps Community Association Managers handle age-restricted requirements consistently.
Texas: Mix of Market-Rate and Income-Restricted 55+ Housing
- Requirements often mirror national averages, with wide variation by property type.
- Income-restricted (LIHTC) 55+ communities in Texas, such as Arbor Park in Austin, de-emphasize credit scores in favor of income verification, and income caps become the main screening factor.
- Market-rate communities in Texas typically require minimum credit scores between 600 and 650, while luxury properties often expect scores above 700.
Ask each community for its written requirements before you apply so you can prepare documents that match those expectations.
Renting vs. Buying: How Requirements Differ
Renters and buyers experience similar checks, but buyers face extra layers of review. The table below highlights the main differences, especially the fact that buyers go through both lender screening and HOA approval.
| Requirement | Renters | Buyers |
|---|---|---|
| Credit score minimum | Typically 600–700, with mid-range communities in the 620–660 range | FHA: 580+; Conventional: 620+; plus the HOA’s own threshold |
| Income verification | Two to three times monthly rent in gross income | Debt-to-income ratio under 45–50%, depending on loan type |
| HOA/association approval | Required | Required, often with stricter standards |
| Additional scrutiny | Rental history and eviction check | Down payment, mortgage preapproval, and lender overlays |
Buyers face two levels of credit review, one from the mortgage lender and another from the HOA. Cash buyers skip the mortgage review but still need association approval.
What to Do If You Don’t Meet the Requirements
Applicants with scores below the typical range or income slightly under the usual guideline still have options. Communities often consider compensating factors when you present them clearly.
- Offer a larger security deposit: Many communities accept a higher deposit when credit is the only concern.
- Bring a co-signer or guarantor: Lenders often expect a co-signer to have a FICO score of 670 or higher, sometimes 700, plus a low debt-to-income ratio and a clean payment history, which can strengthen your file when income is tight.
- Write a letter of explanation: When credit issues come from medical bills, divorce, or a past hardship, a clear explanation helps reviewers understand context.
- Look for communities with lower thresholds: Some properties accept scores in the high 500s or low 600s and focus more on recent payment behavior.
- Improve your credit before applying: Paying bills on time and lowering credit card balances are two of the fastest ways to raise a score.
- Consider income-restricted communities: LIHTC properties often focus more on income caps and less on credit scores, which can help applicants with stable income and past credit issues.
How Communities Manage 55+ Status and Credit Reviews
Many communities rely on specialized platforms to verify age, run credit checks, and keep application steps consistent. Clear, repeatable processes protect both the community and the applicant through fewer delays, clearer communication, and more predictable outcomes.
A standardized verification workflow usually includes:
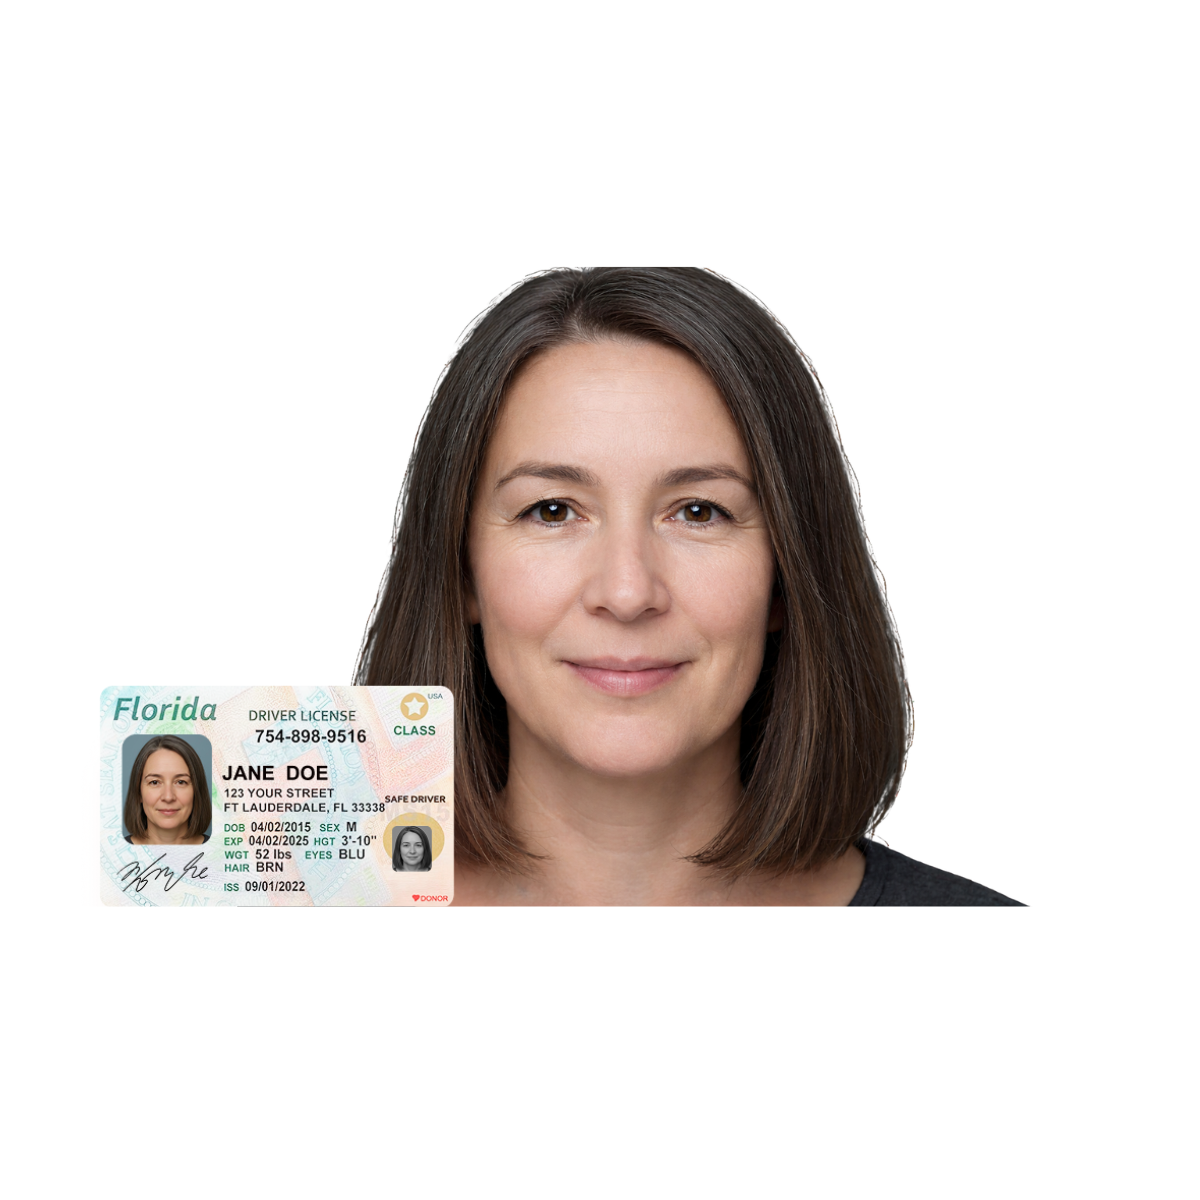
- Age verification: Government-issued ID collected and checked against HOPA requirements.
- Credit check: Pulled through a legitimate credit bureau reseller. TenantEvaluation is a direct reseller of TransUnion and Equifax data and accesses that data under strict bureau rules, with no gray-market or offshore sources.
- Income verification: Documentation collected and reviewed using the same criteria for every applicant.
- Background check: Criminal, eviction, and rental history screened under FCRA guidelines, with built-in adverse action workflows.
- Documentation: All records stored securely with a clear audit trail.
TenantEvaluation’s 55+ Communities Verification platform helps Florida condos and HOAs manage age-restricted applications in a consistent way. It reduces manual work, supports documentation consistency, and strengthens internal processes so Community Association Managers can focus more on residents and less on paperwork.
FAQ: Your Questions Answered
What Is the 80/20 Rule in a 55+ Community?
The 80/20 rule, created under the Housing for Older Persons Act (HOPA), requires that at least 80% of occupied units in a 55+ community have at least one resident aged 55 or older. The remaining 20% can be occupied by younger residents, as long as the 80% threshold stays intact so the community keeps its HOPA exemption from familial status discrimination claims. Communities must verify age with reliable documentation and conduct occupancy surveys at least every two years to confirm compliance.
How Strict Are 55+ Communities with Credit Checks?
Most 55+ communities use a minimum credit score in the typical 600–700 range mentioned earlier, with some flexibility for strong income or rental history. Exact thresholds vary by property and by whether you rent or buy. Many communities review the full application, including income, rental history, and explanations for past issues, instead of relying only on the score. Luxury or highly competitive properties may expect scores above 700, while some income-restricted LIHTC communities focus more on income verification than on credit scores.
Can I Be Denied for a 55+ Community Due to Credit?
Communities can deny applications based on credit history when they follow FCRA rules. If a denial relies on a screening report, the community must send an adverse action notice that names the screening company. You then have the right to a free copy of the report within 60 days and the right to dispute any inaccuracies. Errors on credit reports occur frequently, and successful disputes can improve the outcome of a later application.
Do 55+ Communities Check Income?
Most 55+ communities verify income to confirm that applicants can afford the rent or HOA fees. The common standard is gross monthly income around two to three times the monthly cost. Acceptable documentation includes tax returns, pension statements, Social Security award letters, bank statements, and investment or retirement account records. Fixed income sources, including Social Security and pension payments, are widely accepted and familiar to communities that serve older residents.
What Documents Do I Need to Prove Age?
Communities usually accept a driver’s license, passport, birth certificate, or other government-issued identification to confirm that you are 55 or older. Under HOPA, communities must verify age through reliable documentation and keep those records in an auditable format. Age verification happens separately from financial screening, so you need both age documentation and financial approval.
Your Path to the Right 55+ Community
Here is a quick recap of the main points:
- Credit scores: Most 55+ communities use minimums in the typical 600–700 range, with options for applicants who bring stronger deposits, co-signers, or choose more flexible communities.
- Income: Communities usually look for income around two to three times the monthly rent or HOA fee, and fixed income counts when it is well documented.
- Background checks: Criminal, eviction, and credit history checks are standard, and FCRA rights protect you throughout the process.
- Age verification: HOPA’s 80/20 rule requires proof that you meet the 55+ standard, handled alongside but separate from financial review.
- State variations: Florida and Texas communities set their own credit and income rules within federal guidelines, so always confirm details in writing.
- Options: Larger deposits, co-signers, letters of explanation, and alternative communities can help when your application is not perfect.
With preparation and clear documentation, you can match your financial situation to a community that fits your lifestyle.
For communities managing 55+ applications, TenantEvaluation’s 55+ Communities Verification platform helps Florida condos and HOAs handle age-restricted applications consistently, reduce manual work, and improve documentation quality. It is built for Community Association Managers and reflects how Florida associations operate in practice.
Ready to streamline your 55+ community verification process? Talk to our team and explore a live demo.
